Limitation for consequential assessments runs from prescribed authority receipt, while verified purchases cannot be disallowed merely for unanswered s...
Higher depreciation for qualifying commercial vehicles, exempt-income disallowance, research deduction verification, and club-expense treatment clarif...
Charitable registration renewal cannot become an assessment of receipts, profitability or annual exemption compliance, requiring renewal and donation ...
AMP expenditure for own business is not an international transaction without an associated-enterprise arrangement, eliminating transfer pricing adjust...
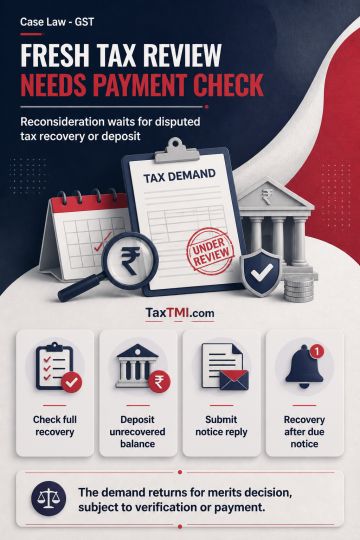
Fresh adjudication of a confirmed tax demand may proceed only after verification that the entire disputed tax has been recovered or after deposit of any unrecovered balance. The demand was remitted for a final decision on merits, conditional on verification or payment of the disputed tax and submission of a reply to the show-cause notice with supporting documents. If those conditions were not met, recovery could continue in accordance with law after due notice.
Fresh adjudication of a confirmed tax demand may proceed only after verification that the entire disputed tax has been recovered or after deposit of any unrecovered balance. The demand was remitted for a final decision on merits, conditional on verification or payment of the disputed tax and submission of a reply to the show-cause notice with supporting documents. If those conditions were not met, recovery could continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925