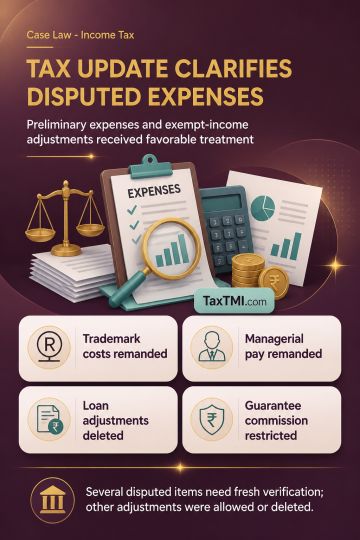
Preliminary-expense amortisation and MAT exempt-income adjustments prevailed, while trademark costs and managerial remuneration require fresh verifica...
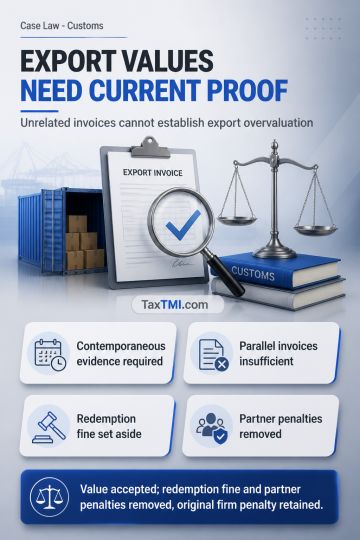
Export valuation requires contemporaneous evidence; unrelated invoices cannot prove overvaluation, and dual penalties on firm and partner are impermis...
Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
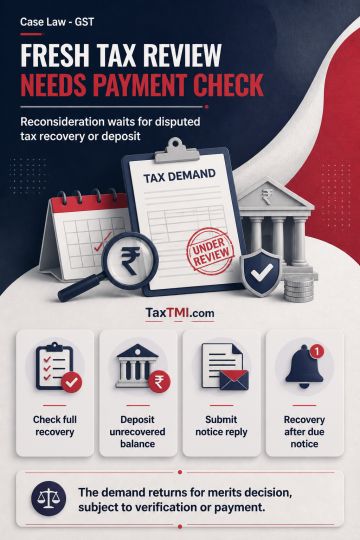
Fresh adjudication of a confirmed tax demand may proceed only after verification that the entire disputed tax has been recovered or after deposit of any unrecovered balance. The demand was remitted for a final decision on merits, conditional on verification or payment of the disputed tax and submission of a reply to the show-cause notice with supporting documents. If those conditions were not met, recovery could continue in accordance with law after due notice.
Fresh adjudication of a confirmed tax demand may proceed only after verification that the entire disputed tax has been recovered or after deposit of any unrecovered balance. The demand was remitted for a final decision on merits, conditional on verification or payment of the disputed tax and submission of a reply to the show-cause notice with supporting documents. If those conditions were not met, recovery could continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896