Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
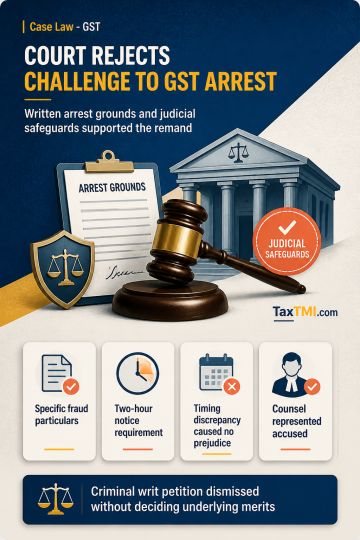
Article 22(1) requires written communication of arrest grounds within a reasonable time and at least two hours before production for remand. Written grounds identifying the accused's alleged role, wrongful input tax credit, entities involved and particulars of fraud were treated as sufficiently specific; refusal to receive them did not render them vague. Conflicting arrest times did not invalidate the arrest where same-day production before the Magistrate caused no prejudice, and recorded reasons to believe were not required to be supplied. Judicial remand was supported by counsel representation, consideration of both sides' submissions, verification of statutory safeguards and recorded satisfaction on the arrest's justification. The criminal writ petition challenging the GST arrest and remand was dismissed without addressing the underlying merits.
Article 22(1) requires written communication of arrest grounds within a reasonable time and at least two hours before production for remand. Written grounds identifying the accused's alleged role, wrongful input tax credit, entities involved and particulars of fraud were treated as sufficiently specific; refusal to receive them did not render them vague. Conflicting arrest times did not invalidate the arrest where same-day production before the Magistrate caused no prejudice, and recorded reasons to believe were not required to be supplied. Judicial remand was supported by counsel representation, consideration of both sides' submissions, verification of statutory safeguards and recorded satisfaction on the arrest's justification. The criminal writ petition challenging the GST arrest and remand was dismissed without addressing the underlying merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881