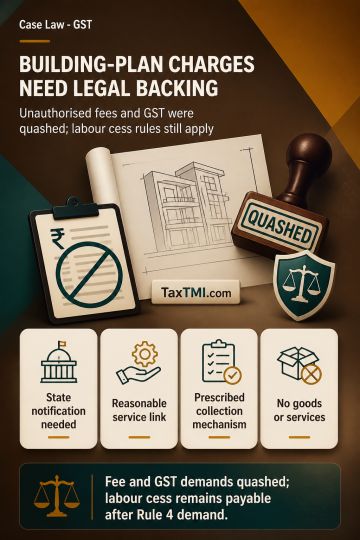
Building-plan sanction charges require statutory authority; unauthorised fees and GST were quashed, while labour cess must follow prescribed collectio...
Pure-agent exclusion fails where hotel booking facilitators receive third-party services themselves, making entire customer consideration taxable as r...
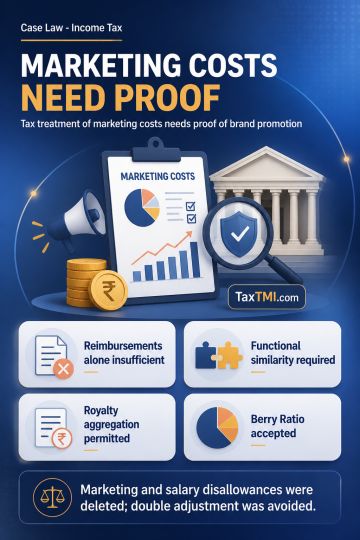
Transfer pricing requires evidence for AMP transactions, functionally reliable comparables, and appropriate aggregation or Berry Ratio benchmarking me...
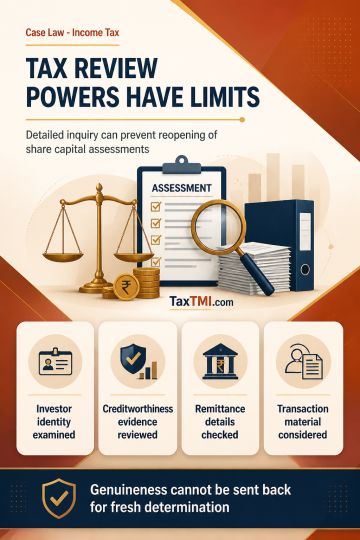
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is establ...
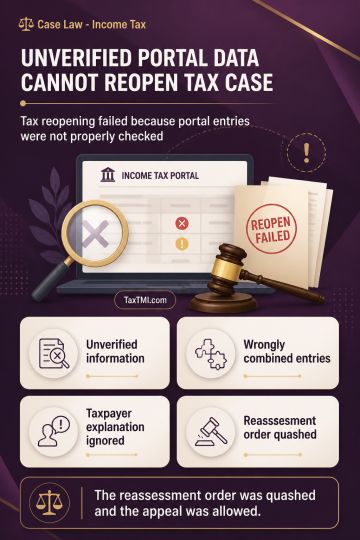
Reassessment jurisdiction fails where unverified portal information is aggregated without examining the taxpayer's explanation or relevance of entries...
Statutory sanction for delayed reassessment requires approval from the prescribed authority; approval by an inferior authority invalidates jurisdictio...
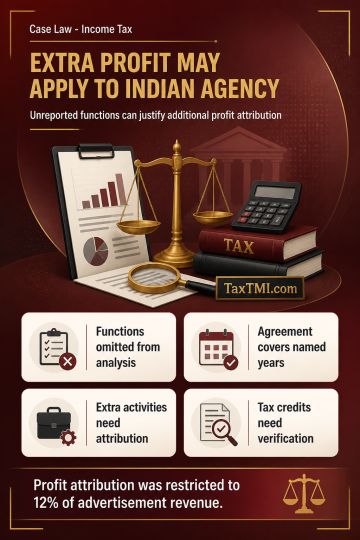
Transfer pricing margin adjustments require matching treatment of non-operating income and related costs, with comparability issues reconsidered on ev...
Page of 4896
Press 'Enter' after typing page number.
2041 to 2060 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
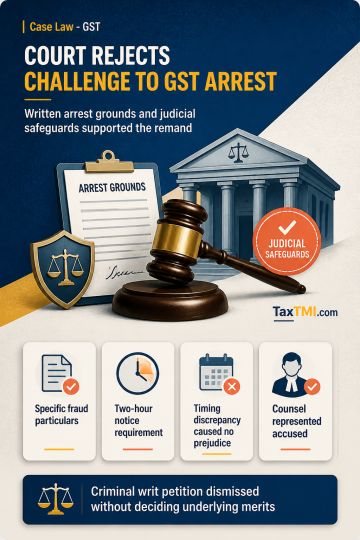
Article 22(1) requires written communication of arrest grounds within a reasonable time and at least two hours before production for remand. Written grounds identifying the accused's alleged role, wrongful input tax credit, entities involved and particulars of fraud were treated as sufficiently specific; refusal to receive them did not render them vague. Conflicting arrest times did not invalidate the arrest where same-day production before the Magistrate caused no prejudice, and recorded reasons to believe were not required to be supplied. Judicial remand was supported by counsel representation, consideration of both sides' submissions, verification of statutory safeguards and recorded satisfaction on the arrest's justification. The criminal writ petition challenging the GST arrest and remand was dismissed without addressing the underlying merits.
Article 22(1) requires written communication of arrest grounds within a reasonable time and at least two hours before production for remand. Written grounds identifying the accused's alleged role, wrongful input tax credit, entities involved and particulars of fraud were treated as sufficiently specific; refusal to receive them did not render them vague. Conflicting arrest times did not invalidate the arrest where same-day production before the Magistrate caused no prejudice, and recorded reasons to believe were not required to be supplied. Judicial remand was supported by counsel representation, consideration of both sides' submissions, verification of statutory safeguards and recorded satisfaction on the arrest's justification. The criminal writ petition challenging the GST arrest and remand was dismissed without addressing the underlying merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896