Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
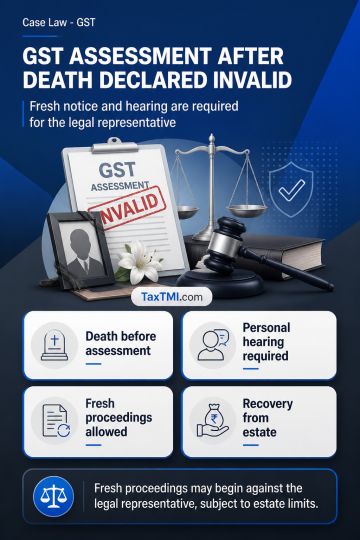
GST assessment against a deceased proprietor has no legal efficacy, particularly where it is completed without the statutory personal-hearing opportunity under Section 75(4). The assessment order and consequential appellate rejection were declared invalid because the assessment followed the proprietor's death and did not address the hearing requirement. Fresh assessment proceedings may be initiated by issuing notice and providing a hearing to the legal representative or person carrying on the business. Recovery is limited to the deceased person's available estate, and the intervening period may be excluded when computing limitation for fresh proceedings.
GST assessment against a deceased proprietor has no legal efficacy, particularly where it is completed without the statutory personal-hearing opportunity under Section 75(4). The assessment order and consequential appellate rejection were declared invalid because the assessment followed the proprietor's death and did not address the hearing requirement. Fresh assessment proceedings may be initiated by issuing notice and providing a hearing to the legal representative or person carrying on the business. Recovery is limited to the deceased person's available estate, and the intervening period may be excluded when computing limitation for fresh proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888