Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
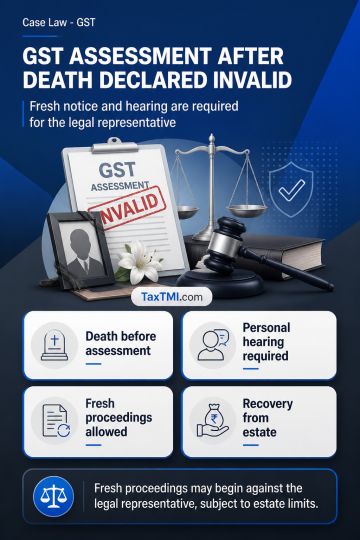
GST assessment against a deceased proprietor has no legal efficacy, particularly where it is completed without the statutory personal-hearing opportunity under Section 75(4). The assessment order and consequential appellate rejection were declared invalid because the assessment followed the proprietor's death and did not address the hearing requirement. Fresh assessment proceedings may be initiated by issuing notice and providing a hearing to the legal representative or person carrying on the business. Recovery is limited to the deceased person's available estate, and the intervening period may be excluded when computing limitation for fresh proceedings.
GST assessment against a deceased proprietor has no legal efficacy, particularly where it is completed without the statutory personal-hearing opportunity under Section 75(4). The assessment order and consequential appellate rejection were declared invalid because the assessment followed the proprietor's death and did not address the hearing requirement. Fresh assessment proceedings may be initiated by issuing notice and providing a hearing to the legal representative or person carrying on the business. Recovery is limited to the deceased person's available estate, and the intervening period may be excluded when computing limitation for fresh proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897