Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
Assessment proceedings and an appellate order against a sole...
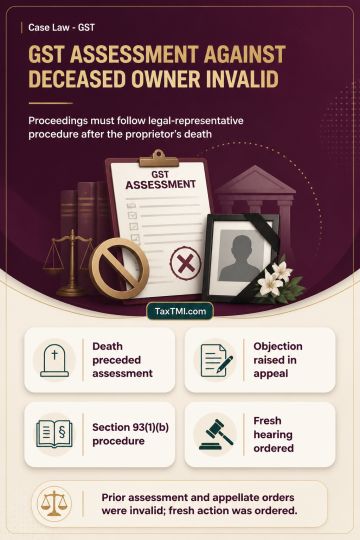
Assessment against deceased sole proprietor requires proceedings against the legal representative, rendering prior assessment and appellate orders invalid.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Assessment proceedings and an appellate order against a sole proprietorship were invalid because the proprietor had died before the assessment order was issued and the objection was raised in appeal. Where GST liability is pursued after a sole proprietor's death, the assessing authority must follow the procedure under Section 93(1)(b) of the CGST Act against the legal representative. The common appellate order was set aside, and the matter was remanded for fresh action against the legal representative after an opportunity of hearing.
Assessment proceedings and an appellate order against a sole proprietorship were invalid because the proprietor had died before the assessment order was issued and the objection was raised in appeal. Where GST liability is pursued after a sole proprietor's death, the assessing authority must follow the procedure under Section 93(1)(b) of the CGST Act against the legal representative. The common appellate order was set aside, and the matter was remanded for fresh action against the legal representative after an opportunity of hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881