Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Page of 4935
Press 'Enter' after typing page number.
2081 to 2100 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
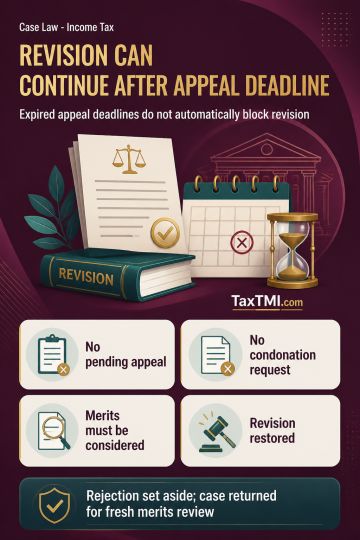
Section 264(4) does not bar revision merely because the statutory period for filing an appeal has expired. Where no appeal or condonation application is pending and waiver of appeal is not relevant, the Revisional Authority should entertain the revision on merits. Refusal on the premise that the revision is non-maintainable is erroneous, and merits observations founded on that premise cannot stand. The rejection was set aside, with the revision restored for fresh adjudication on merits; all substantive contentions remain open.
Section 264(4) does not bar revision merely because the statutory period for filing an appeal has expired. Where no appeal or condonation application is pending and waiver of appeal is not relevant, the Revisional Authority should entertain the revision on merits. Refusal on the premise that the revision is non-maintainable is erroneous, and merits observations founded on that premise cannot stand. The rejection was set aside, with the revision restored for fresh adjudication on merits; all substantive contentions remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935