Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
Stakeholder-list modification permits liquidators to update entries on new information, subject to notifying the Adjudicating Authority within prescri...
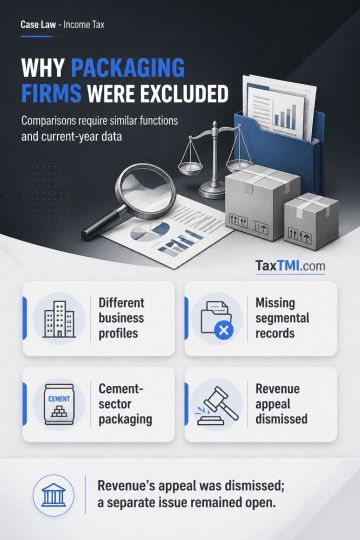
Transfer-pricing comparability requires functional similarity and reliable current-year segmental data. Bilcare Ltd. was excluded because of diversified operations, unavailable segmental data, and its pharmaceutical packaging profile, which differed from paper-based aseptic packaging for food and drink products. Karur KCP Packaging Ltd. was excluded because it produced kraft paper and polypropylene bags principally for the cement industry, making its products materially dissimilar. Earlier-year segmental data could not support current-year inclusion where relevant data was unavailable. The Tribunal's fact-based comparability findings disclosed neither error nor perversity, so no substantial question of law arose and the Revenue's appeal was dismissed; the separate Revenue appeal issue remained open.
Transfer-pricing comparability requires functional similarity and reliable current-year segmental data. Bilcare Ltd. was excluded because of diversified operations, unavailable segmental data, and its pharmaceutical packaging profile, which differed from paper-based aseptic packaging for food and drink products. Karur KCP Packaging Ltd. was excluded because it produced kraft paper and polypropylene bags principally for the cement industry, making its products materially dissimilar. Earlier-year segmental data could not support current-year inclusion where relevant data was unavailable. The Tribunal's fact-based comparability findings disclosed neither error nor perversity, so no substantial question of law arose and the Revenue's appeal was dismissed; the separate Revenue appeal issue remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888