Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
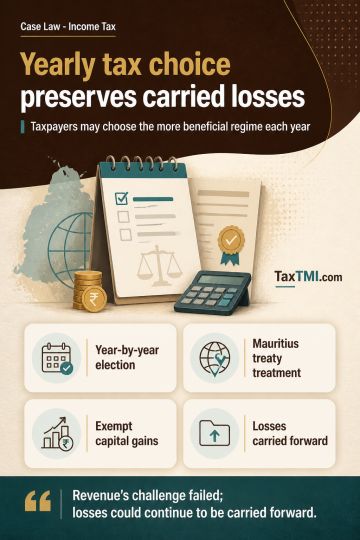
Annual election between the Income-tax Act and the applicable tax treaty permits an assessee to select the more beneficial regime independently for each assessment year, with no identified bar on changing that option across years. Where treaty treatment under the India-Mauritius DTAA renders capital gains non-taxable in India, earlier short-term capital losses validly carried forward need not be set off against those exempt gains. Those losses may therefore continue to be carried forward. The Revenue's challenge to further carry forward of the losses failed on merits, while the reassessment challenge became infructuous.
Annual election between the Income-tax Act and the applicable tax treaty permits an assessee to select the more beneficial regime independently for each assessment year, with no identified bar on changing that option across years. Where treaty treatment under the India-Mauritius DTAA renders capital gains non-taxable in India, earlier short-term capital losses validly carried forward need not be set off against those exempt gains. Those losses may therefore continue to be carried forward. The Revenue's challenge to further carry forward of the losses failed on merits, while the reassessment challenge became infructuous.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI