Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
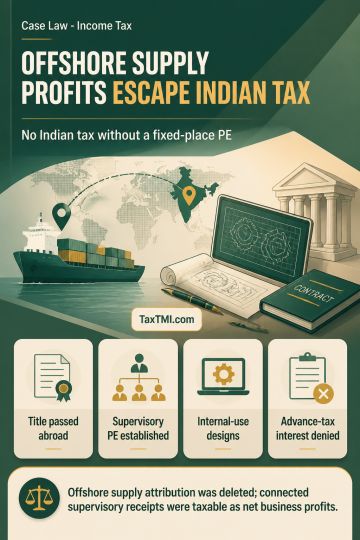
Offshore supply profits from equipment, integrated designs and spares manufactured, delivered FOB and paid for outside India were not taxable in India where title passed abroad, no fixed-place PE was established, and the supervisory PE had no connection with the supplies. The attribution of those profits was deleted. Supervisory services exceeding the treaty duration threshold created a supervisory PE; receipts directly connected with it were taxable as net business profits under Article 7, not gross-basis fees for technical services. Offshore designs and drawings supplied solely for internal plant use transferred no right to commercially exploit intellectual property and were business income, not royalty or fees for technical services. Advance-tax interest was not chargeable for the relevant period, while return-delay interest and tax-deduction credit required verification.
Offshore supply profits from equipment, integrated designs and spares manufactured, delivered FOB and paid for outside India were not taxable in India where title passed abroad, no fixed-place PE was established, and the supervisory PE had no connection with the supplies. The attribution of those profits was deleted. Supervisory services exceeding the treaty duration threshold created a supervisory PE; receipts directly connected with it were taxable as net business profits under Article 7, not gross-basis fees for technical services. Offshore designs and drawings supplied solely for internal plant use transferred no right to commercially exploit intellectual property and were business income, not royalty or fees for technical services. Advance-tax interest was not chargeable for the relevant period, while return-delay interest and tax-deduction credit required verification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881