Concessional penalty for search-disclosed unreconciled jewellery applies where substantive disclosure conditions are met despite omission from origina...
Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
Authorised courier due diligence protects against penalties where declared exports conceal prohibited goods despite proper documentation and customs p...
Page of 4931
Press 'Enter' after typing page number.
2121 to 2140 of 98613 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
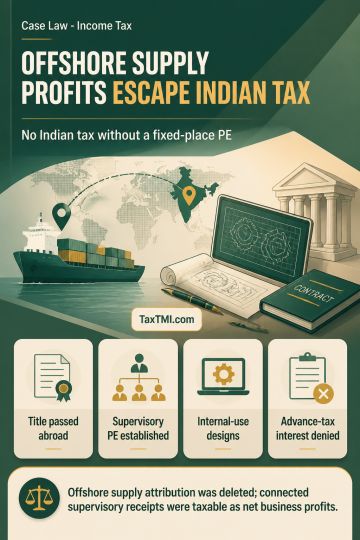
Offshore supply profits from equipment, integrated designs and spares manufactured, delivered FOB and paid for outside India were not taxable in India where title passed abroad, no fixed-place PE was established, and the supervisory PE had no connection with the supplies. The attribution of those profits was deleted. Supervisory services exceeding the treaty duration threshold created a supervisory PE; receipts directly connected with it were taxable as net business profits under Article 7, not gross-basis fees for technical services. Offshore designs and drawings supplied solely for internal plant use transferred no right to commercially exploit intellectual property and were business income, not royalty or fees for technical services. Advance-tax interest was not chargeable for the relevant period, while return-delay interest and tax-deduction credit required verification.
Offshore supply profits from equipment, integrated designs and spares manufactured, delivered FOB and paid for outside India were not taxable in India where title passed abroad, no fixed-place PE was established, and the supervisory PE had no connection with the supplies. The attribution of those profits was deleted. Supervisory services exceeding the treaty duration threshold created a supervisory PE; receipts directly connected with it were taxable as net business profits under Article 7, not gross-basis fees for technical services. Offshore designs and drawings supplied solely for internal plant use transferred no right to commercially exploit intellectual property and were business income, not royalty or fees for technical services. Advance-tax interest was not chargeable for the relevant period, while return-delay interest and tax-deduction credit required verification.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931