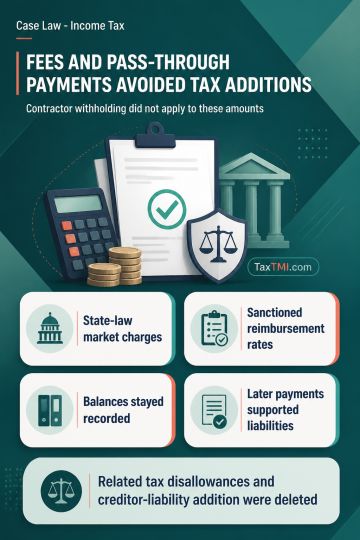
Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
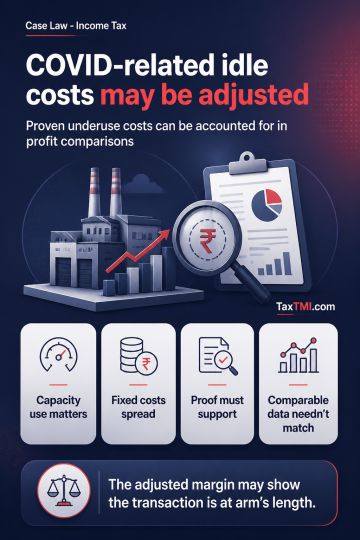
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
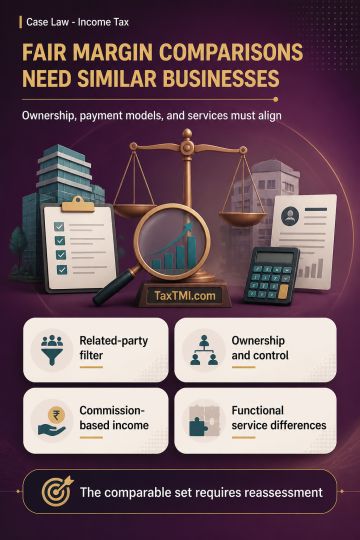
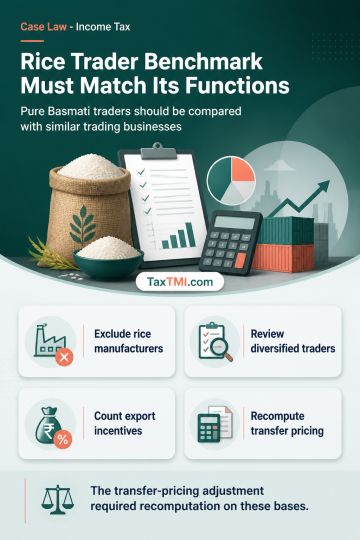
TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
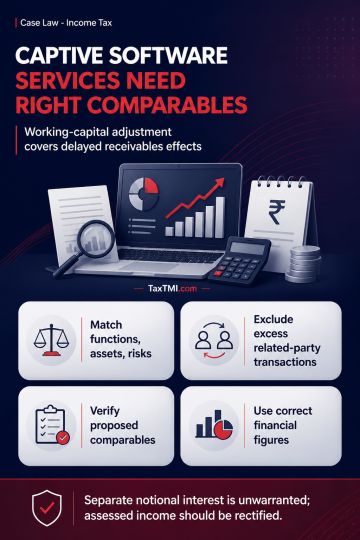
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Page of 4910
Press 'Enter' after typing page number.
1801 to 1820 of 98196 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Penalty proceedings for concealment require the Assessing Officer to reach satisfaction during assessment; a later notice cannot replace that jurisdictional requirement. Section 271(1) uses "may", preserving discretion and preventing automatic penalty merely because additional income is declared in returns filed under section 148. The deeming fiction in section 271(1B) applies strictly only where an addition or disallowance is made and the assessment order contains a clear direction to initiate penalty. A statement that proceedings "will be initiated separately" is only a future intention. Explanation 5A may deem concealment in specified circumstances but cannot cure invalid initiation or make penalty automatic. Penalties were deleted, while their merits remained open.
Penalty proceedings for concealment require the Assessing Officer to reach satisfaction during assessment; a later notice cannot replace that jurisdictional requirement. Section 271(1) uses "may", preserving discretion and preventing automatic penalty merely because additional income is declared in returns filed under section 148. The deeming fiction in section 271(1B) applies strictly only where an addition or disallowance is made and the assessment order contains a clear direction to initiate penalty. A statement that proceedings "will be initiated separately" is only a future intention. Explanation 5A may deem concealment in specified circumstances but cannot cure invalid initiation or make penalty automatic. Penalties were deleted, while their merits remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910