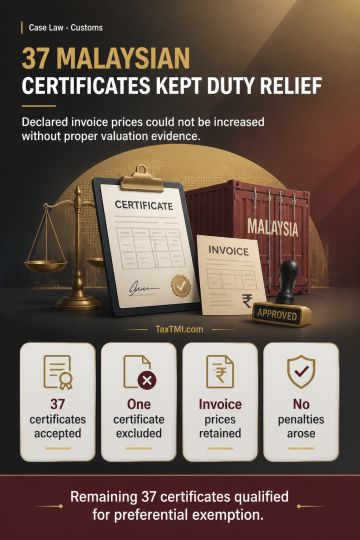
Country of Origin Certificates and declared transaction value supported preferential customs exemption where authenticity and invoice prices remained ...
Online bond platforms may offer overseas-regulated products and tax-specific bonds subject to disclosures, compliance safeguards and revised complianc...
Corporate guarantee valuation permits actual ascertainable commission while barring retroactive application and extended-period penalties for bona fid...
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through w...
Transitioned CENVAT credit may validly satisfy mandatory pre-deposit requirements for legacy service tax appeals through Electronic Credit Ledger debi...
Building-plan sanction charges require statutory authority; unauthorised fees and GST were quashed, while labour cess must follow prescribed collectio...
Penalty proceedings for concealment require the Assessing Officer to reach satisfaction during assessment; a later notice cannot replace that jurisdictional requirement. Section 271(1) uses "may", preserving discretion and preventing automatic penalty merely because additional income is declared in returns filed under section 148. The deeming fiction in section 271(1B) applies strictly only where an addition or disallowance is made and the assessment order contains a clear direction to initiate penalty. A statement that proceedings "will be initiated separately" is only a future intention. Explanation 5A may deem concealment in specified circumstances but cannot cure invalid initiation or make penalty automatic. Penalties were deleted, while their merits remained open.
Penalty proceedings for concealment require the Assessing Officer to reach satisfaction during assessment; a later notice cannot replace that jurisdictional requirement. Section 271(1) uses "may", preserving discretion and preventing automatic penalty merely because additional income is declared in returns filed under section 148. The deeming fiction in section 271(1B) applies strictly only where an addition or disallowance is made and the assessment order contains a clear direction to initiate penalty. A statement that proceedings "will be initiated separately" is only a future intention. Explanation 5A may deem concealment in specified circumstances but cannot cure invalid initiation or make penalty automatic. Penalties were deleted, while their merits remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897