Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscr...
Anonymous donation classification fails where charitable trusts maintain undisputed donor identity records and evidence corpus contributions' intended...
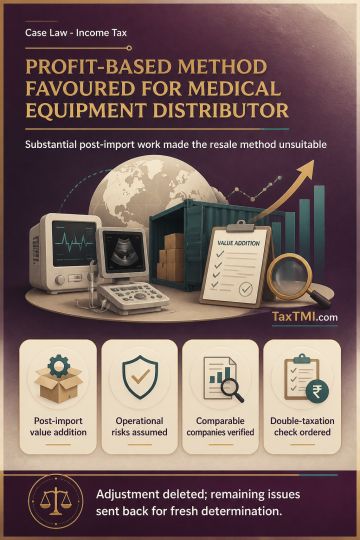
Transfer pricing method selection favours TNMM where medical-equipment distribution involves substantial post-import value addition and operational ri...
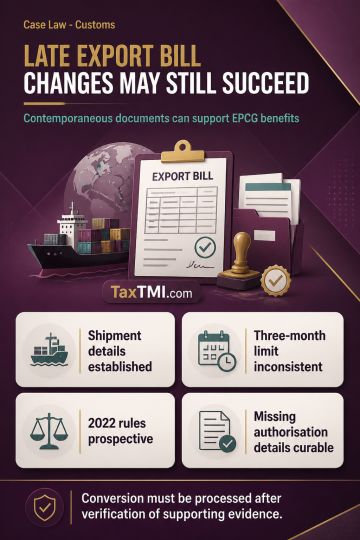
Post-export shipping bill conversion remains available where contemporaneous evidence supports EPCG benefits despite curable procedural omissions and ...
Composite letting of commercial premises, amenities and permanently embedded fixtures is assessable as income from house property where the ancillary agreements are integral to and co-terminus with the principal leave-and-licence arrangement. The substance of the arrangement and the parties' dominant intention prevail over separate documentation or apportionment of consideration; amenities not independently exploitable remain part of the integrated commercial unit. Such assessment permits the standard deduction for house property income. Interest on a refinanced loan remains deductible where it replaces acquisition-related borrowing, the funds are traceable to property acquisition, and no diversion to a non-qualifying purpose is established, subject to arithmetical verification of utilisation.
Composite letting of commercial premises, amenities and permanently embedded fixtures is assessable as income from house property where the ancillary agreements are integral to and co-terminus with the principal leave-and-licence arrangement. The substance of the arrangement and the parties' dominant intention prevail over separate documentation or apportionment of consideration; amenities not independently exploitable remain part of the integrated commercial unit. Such assessment permits the standard deduction for house property income. Interest on a refinanced loan remains deductible where it replaces acquisition-related borrowing, the funds are traceable to property acquisition, and no diversion to a non-qualifying purpose is established, subject to arithmetical verification of utilisation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897