Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
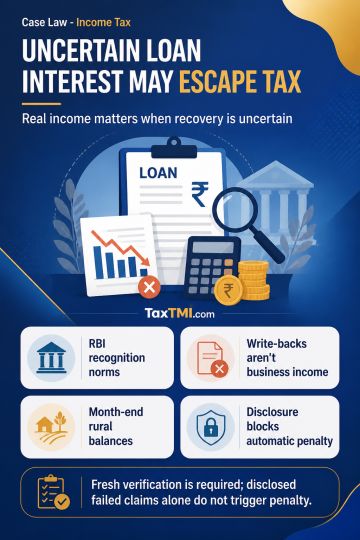
Interest on non-performing assets of a co-operative bank is not taxable on notional accrual where recovery is uncertain and RBI prudential norms govern recognition, notwithstanding mercantile accounting. Reversal of a provision for bad and doubtful debts on an asset becoming performing is not deemed business income where it is neither recovery of an allowed bad debt nor remission of a loss, expenditure or trading liability. Provisions for standard assets may qualify for deduction as bad-debt provisions, subject to the statutory ceiling; rural advances must be computed using month-end outstanding balances, and fresh provisions cannot be netted against write-backs. Quantification requires fresh verification. Penalty does not arise merely because a disclosed deduction claim fails for lack of a book provision, absent concealment or inaccurate particulars.
Interest on non-performing assets of a co-operative bank is not taxable on notional accrual where recovery is uncertain and RBI prudential norms govern recognition, notwithstanding mercantile accounting. Reversal of a provision for bad and doubtful debts on an asset becoming performing is not deemed business income where it is neither recovery of an allowed bad debt nor remission of a loss, expenditure or trading liability. Provisions for standard assets may qualify for deduction as bad-debt provisions, subject to the statutory ceiling; rural advances must be computed using month-end outstanding balances, and fresh provisions cannot be netted against write-backs. Quantification requires fresh verification. Penalty does not arise merely because a disclosed deduction claim fails for lack of a book provision, absent concealment or inaccurate particulars.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891