Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
Page of 4888
Press 'Enter' after typing page number.
281 to 300 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
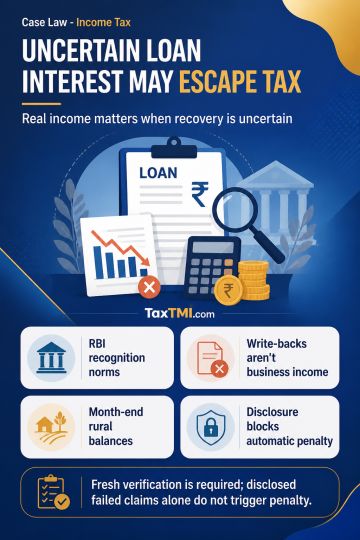
Interest on non-performing assets of a co-operative bank is not taxable on notional accrual where recovery is uncertain and RBI prudential norms govern recognition, notwithstanding mercantile accounting. Reversal of a provision for bad and doubtful debts on an asset becoming performing is not deemed business income where it is neither recovery of an allowed bad debt nor remission of a loss, expenditure or trading liability. Provisions for standard assets may qualify for deduction as bad-debt provisions, subject to the statutory ceiling; rural advances must be computed using month-end outstanding balances, and fresh provisions cannot be netted against write-backs. Quantification requires fresh verification. Penalty does not arise merely because a disclosed deduction claim fails for lack of a book provision, absent concealment or inaccurate particulars.
Interest on non-performing assets of a co-operative bank is not taxable on notional accrual where recovery is uncertain and RBI prudential norms govern recognition, notwithstanding mercantile accounting. Reversal of a provision for bad and doubtful debts on an asset becoming performing is not deemed business income where it is neither recovery of an allowed bad debt nor remission of a loss, expenditure or trading liability. Provisions for standard assets may qualify for deduction as bad-debt provisions, subject to the statutory ceiling; rural advances must be computed using month-end outstanding balances, and fresh provisions cannot be netted against write-backs. Quantification requires fresh verification. Penalty does not arise merely because a disclosed deduction claim fails for lack of a book provision, absent concealment or inaccurate particulars.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888