Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
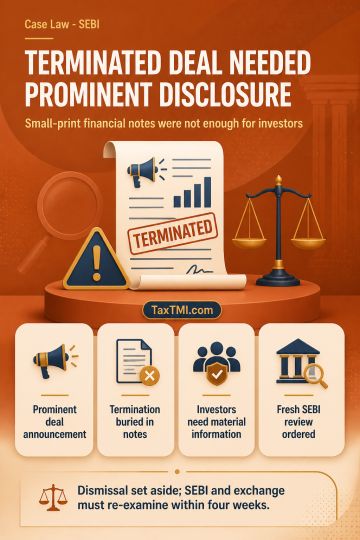
Termination of a share purchase agreement required prominent disclosure under the LODR Regulations where the listed entity had conspicuously announced approval of the acquisition. Mentioning the termination only in small print within a note to unaudited financial results, rather than in the principal board-meeting communication, was treated as no disclosure because investors rely on information about financial position, proposed ventures and collaborations. The complaint-dismissal communication was set aside, and SEBI and the stock exchange were directed to re-examine the mandatory-disclosure issue and issue appropriate orders within four weeks.
Termination of a share purchase agreement required prominent disclosure under the LODR Regulations where the listed entity had conspicuously announced approval of the acquisition. Mentioning the termination only in small print within a note to unaudited financial results, rather than in the principal board-meeting communication, was treated as no disclosure because investors rely on information about financial position, proposed ventures and collaborations. The complaint-dismissal communication was set aside, and SEBI and the stock exchange were directed to re-examine the mandatory-disclosure issue and issue appropriate orders within four weeks.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881