Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
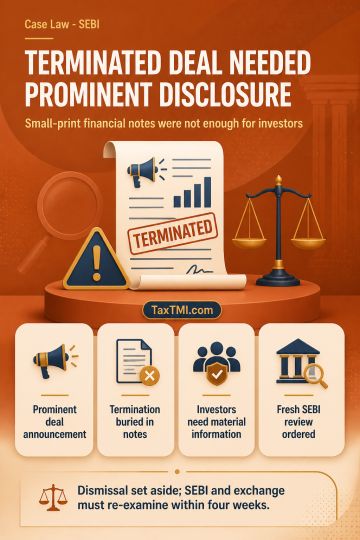
Termination of a share purchase agreement required prominent disclosure under the LODR Regulations where the listed entity had conspicuously announced approval of the acquisition. Mentioning the termination only in small print within a note to unaudited financial results, rather than in the principal board-meeting communication, was treated as no disclosure because investors rely on information about financial position, proposed ventures and collaborations. The complaint-dismissal communication was set aside, and SEBI and the stock exchange were directed to re-examine the mandatory-disclosure issue and issue appropriate orders within four weeks.
Termination of a share purchase agreement required prominent disclosure under the LODR Regulations where the listed entity had conspicuously announced approval of the acquisition. Mentioning the termination only in small print within a note to unaudited financial results, rather than in the principal board-meeting communication, was treated as no disclosure because investors rely on information about financial position, proposed ventures and collaborations. The complaint-dismissal communication was set aside, and SEBI and the stock exchange were directed to re-examine the mandatory-disclosure issue and issue appropriate orders within four weeks.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI