Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
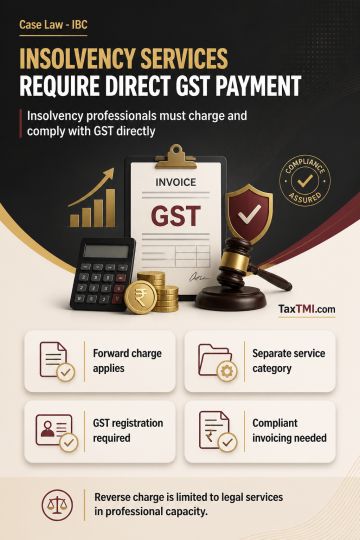
GST liability for insolvency and receivership services depends on the nature and specific classification of the service, not on whether the Insolvency Professional is enrolled as an Advocate. Insolvency Professionals constitute a distinct statutory class under the Insolvency and Bankruptcy Code and IBBI Regulations, and their services are separately classified from legal services. Applying the principle that a specific service description prevails over a general one, services rendered by an Advocate as an Interim Resolution Professional fall outside the reverse-charge category for legal services. Forward charge therefore applies, requiring GST registration, compliant invoicing and related compliance; reverse charge remains limited to legal services rendered in the Advocate's professional capacity.
GST liability for insolvency and receivership services depends on the nature and specific classification of the service, not on whether the Insolvency Professional is enrolled as an Advocate. Insolvency Professionals constitute a distinct statutory class under the Insolvency and Bankruptcy Code and IBBI Regulations, and their services are separately classified from legal services. Applying the principle that a specific service description prevails over a general one, services rendered by an Advocate as an Interim Resolution Professional fall outside the reverse-charge category for legal services. Forward charge therefore applies, requiring GST registration, compliant invoicing and related compliance; reverse charge remains limited to legal services rendered in the Advocate's professional capacity.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881