Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
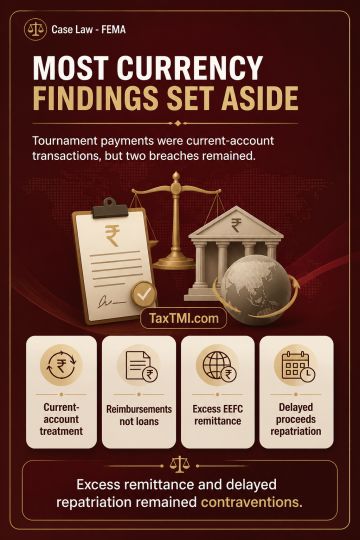
Current account treatment of overseas tournament services removed most FEMA findings, but excess EEFC remittance and delayed repatriation remained bre...
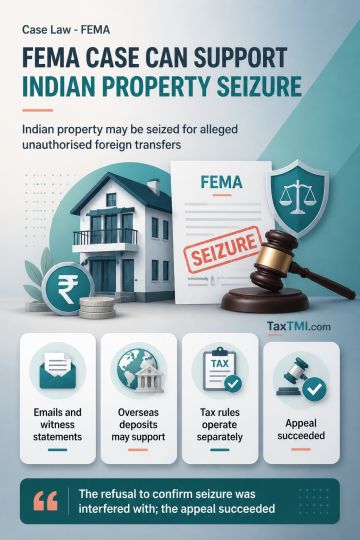
Section 37A of FEMA permits seizure where available material establishes a prima facie Section 4 contravention; final proof is reserved for adjudication. Tally data, emails, witness statements and overseas bank deposits may support an allegation of unauthorised foreign-exchange transfers without proving the ultimate use of every remitted amount. Property in India may be seized at equivalent value even where overseas accounts are held by a separate foreign entity, because that entity's legal personality does not displace FEMA's seizure power against the alleged contravener. Income-tax settlement provisions operate separately and do not override FEMA consequences. The refusal to confirm seizure was therefore interfered with and the appeal succeeded.
Section 37A of FEMA permits seizure where available material establishes a prima facie Section 4 contravention; final proof is reserved for adjudication. Tally data, emails, witness statements and overseas bank deposits may support an allegation of unauthorised foreign-exchange transfers without proving the ultimate use of every remitted amount. Property in India may be seized at equivalent value even where overseas accounts are held by a separate foreign entity, because that entity's legal personality does not displace FEMA's seizure power against the alleged contravener. Income-tax settlement provisions operate separately and do not override FEMA consequences. The refusal to confirm seizure was therefore interfered with and the appeal succeeded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI