Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
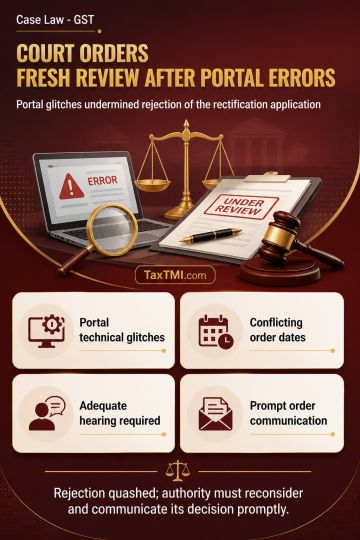
Portal order discrepancies invalidated rectification rejection, requiring fresh reasoned consideration after hearing and prompt communication of the o...
Page of 4935
Press 'Enter' after typing page number.
2541 to 2560 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Time-share accommodation arrangements fall outside Club or...
Time-share accommodation classification excludes Club or Association Service where purchasers receive contractual occupancy rights without genuine membership attributes.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Time-share accommodation arrangements fall outside Club or Association Service where purchasers receive only contractual occupancy rights for specified periods, without ownership, voting, management or other club-membership rights. Contractual use of the term "member" does not determine classification; consideration linked to accommodation categories, absence of conventional subscriptions and resort access for ordinary guests support treatment as accommodation services. A later distinct taxable entry for short-term accommodation further supports that conclusion. Pre-notice payment of tax and applicable interest, absent fraud, collusion or wilful suppression, attracts statutory protection and precludes penalty-only proceedings. Suppression penalties also require evidence of deliberate evasion, not merely a bona fide classification dispute disclosed in regular audited accounts.
Time-share accommodation arrangements fall outside Club or Association Service where purchasers receive only contractual occupancy rights for specified periods, without ownership, voting, management or other club-membership rights. Contractual use of the term "member" does not determine classification; consideration linked to accommodation categories, absence of conventional subscriptions and resort access for ordinary guests support treatment as accommodation services. A later distinct taxable entry for short-term accommodation further supports that conclusion. Pre-notice payment of tax and applicable interest, absent fraud, collusion or wilful suppression, attracts statutory protection and precludes penalty-only proceedings. Suppression penalties also require evidence of deliberate evasion, not merely a bona fide classification dispute disclosed in regular audited accounts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935