Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
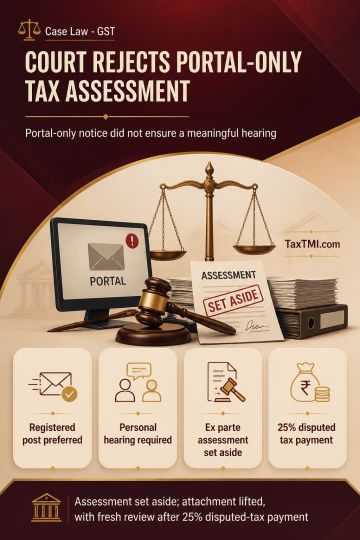
Effective service of GST notices requires more than portal uploading where a taxpayer remains non-responsive despite repeated reminders. Although portal upload constitutes valid service, the assessing officer should consider other statutory modes, preferably registered post with acknowledgement due, to ensure actual communication before making an ex parte assessment. Failure to provide a meaningful opportunity of personal hearing can invalidate the assessment. The High Court set aside the ex parte assessment and lifted the consequential attachment, remanding the matter for fresh merits consideration subject to payment of 25% of the disputed tax. The taxpayer may file objections, and the officer must give clear 14 days' notice of personal hearing.
Effective service of GST notices requires more than portal uploading where a taxpayer remains non-responsive despite repeated reminders. Although portal upload constitutes valid service, the assessing officer should consider other statutory modes, preferably registered post with acknowledgement due, to ensure actual communication before making an ex parte assessment. Failure to provide a meaningful opportunity of personal hearing can invalidate the assessment. The High Court set aside the ex parte assessment and lifted the consequential attachment, remanding the matter for fresh merits consideration subject to payment of 25% of the disputed tax. The taxpayer may file objections, and the officer must give clear 14 days' notice of personal hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888