SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
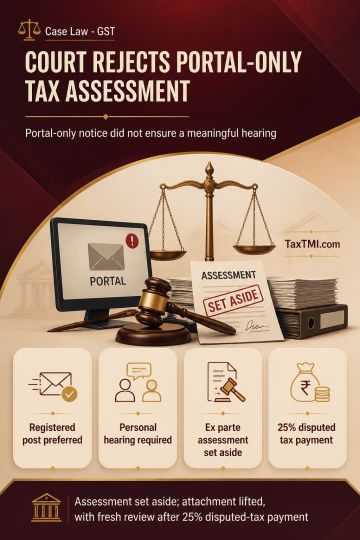
Effective service of GST notices requires more than portal uploading where a taxpayer remains non-responsive despite repeated reminders. Although portal upload constitutes valid service, the assessing officer should consider other statutory modes, preferably registered post with acknowledgement due, to ensure actual communication before making an ex parte assessment. Failure to provide a meaningful opportunity of personal hearing can invalidate the assessment. The High Court set aside the ex parte assessment and lifted the consequential attachment, remanding the matter for fresh merits consideration subject to payment of 25% of the disputed tax. The taxpayer may file objections, and the officer must give clear 14 days' notice of personal hearing.
Effective service of GST notices requires more than portal uploading where a taxpayer remains non-responsive despite repeated reminders. Although portal upload constitutes valid service, the assessing officer should consider other statutory modes, preferably registered post with acknowledgement due, to ensure actual communication before making an ex parte assessment. Failure to provide a meaningful opportunity of personal hearing can invalidate the assessment. The High Court set aside the ex parte assessment and lifted the consequential attachment, remanding the matter for fresh merits consideration subject to payment of 25% of the disputed tax. The taxpayer may file objections, and the officer must give clear 14 days' notice of personal hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883