Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
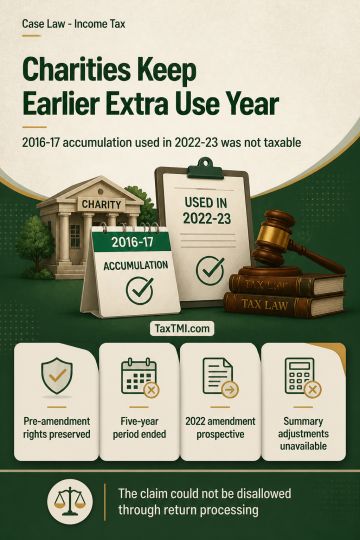
Accumulated charitable income validly set aside under the pre-amendment section 11(2) regime remained available for application in the year immediately following the five-year accumulation period. The Finance Act 2022 omission of that additional utilisation year operated prospectively and did not curtail rights attached to accumulations made earlier. Accordingly, application in financial year 2022-23 of income accumulated in financial year 2016-17 was not deemed taxable income for assessment year 2023-24. Return-processing adjustments cannot disallow such a claim where eligibility depends on reconciling records and resolving debatable questions concerning statutory interpretation and the amendment's temporal operation.
Accumulated charitable income validly set aside under the pre-amendment section 11(2) regime remained available for application in the year immediately following the five-year accumulation period. The Finance Act 2022 omission of that additional utilisation year operated prospectively and did not curtail rights attached to accumulations made earlier. Accordingly, application in financial year 2022-23 of income accumulated in financial year 2016-17 was not deemed taxable income for assessment year 2023-24. Return-processing adjustments cannot disallow such a claim where eligibility depends on reconciling records and resolving debatable questions concerning statutory interpretation and the amendment's temporal operation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927