Territorial jurisdiction in income-tax appeals follows the assessing officer's location, not the Tribunal's seat or a subsequent acquirer's registered...
Transfer pricing comparables must reflect functional similarity, with diverse activities and asset profiles supporting exclusion from contract service...
Real income in electricity distribution excludes surcharges and regulatory assets without reasonably certain recovery, while deductions require return...
Contempt for company bank account restraint breaches requires deliberate disobedience, while contempt appeals are limited to orders imposing punishmen...
Page of 4947
Press 'Enter' after typing page number.
21 to 40 of 98935 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
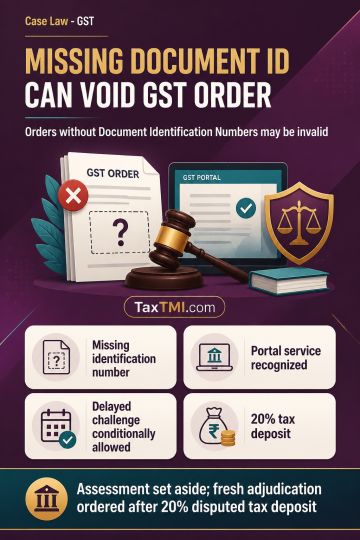
Absence of a Document Identification Number in a GST assessment...
Document Identification Number defects can invalidate GST assessments, with delayed challenges entertained conditionally where patent irregularities exist.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Absence of a Document Identification Number in a GST assessment order is described as an inherent defect that invalidates the order. The text notes that portal upload is a statutory mode of service, and a registered person's ignorance of or inability to access the portal ordinarily does not justify delay. However, it states that delayed writ challenges to assessment orders with patent irregularities may be entertained on deposit of 20% of the disputed tax, balancing taxpayer hardship and tax administration. The assessment was set aside and remanded for fresh adjudication after hearing, with all issues left open, subject to that deposit.
Absence of a Document Identification Number in a GST assessment order is described as an inherent defect that invalidates the order. The text notes that portal upload is a statutory mode of service, and a registered person's ignorance of or inability to access the portal ordinarily does not justify delay. However, it states that delayed writ challenges to assessment orders with patent irregularities may be entertained on deposit of 20% of the disputed tax, balancing taxpayer hardship and tax administration. The assessment was set aside and remanded for fresh adjudication after hearing, with all issues left open, subject to that deposit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4947




 Get Daily Updates