Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
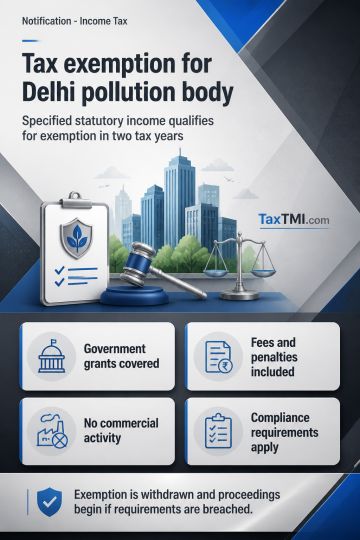
Tax exemption applies to specified income of the Delhi Pollution Control Committee under Schedule III read with section 11 of the Income-tax Act, 2025. Exempt income includes government grants or subsidies, statutory consent, licence and application fees, environmental penalties and fines, and interest on deposits or investments of surplus funds. The exemption applies for tax years 2026-27 and 2027-28, subject to the committee not undertaking commercial activity, filing its income-tax return as prescribed, and maintaining unchanged activities and income character. Non-compliance results in withdrawal of the exemption and initiation of proceedings under the Act.
Tax exemption applies to specified income of the Delhi Pollution Control Committee under Schedule III read with section 11 of the Income-tax Act, 2025. Exempt income includes government grants or subsidies, statutory consent, licence and application fees, environmental penalties and fines, and interest on deposits or investments of surplus funds. The exemption applies for tax years 2026-27 and 2027-28, subject to the committee not undertaking commercial activity, filing its income-tax return as prescribed, and maintaining unchanged activities and income character. Non-compliance results in withdrawal of the exemption and initiation of proceedings under the Act.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915