Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Page of 4923
Press 'Enter' after typing page number.
41 to 60 of 98454 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
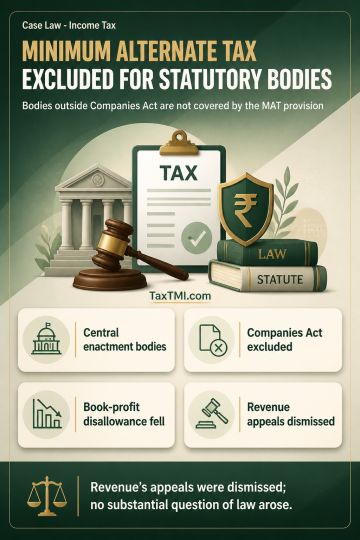
Minimum Alternate Tax under section 115JB does not apply to a statutory body constituted under a Central enactment that is not incorporated under the Companies Act, despite being assessable as a company under the Income-tax Act. Applying the principle that the legal fiction in section 115JB cannot extend to such entities, the High Court found the provision inapplicable. Consequently, the issue of disallowance under section 14A in computing book profit did not survive, as it depended on section 115JB applying. No substantial question of law arose, and the Revenue's appeals were dismissed.
Minimum Alternate Tax under section 115JB does not apply to a statutory body constituted under a Central enactment that is not incorporated under the Companies Act, despite being assessable as a company under the Income-tax Act. Applying the principle that the legal fiction in section 115JB cannot extend to such entities, the High Court found the provision inapplicable. Consequently, the issue of disallowance under section 14A in computing book profit did not survive, as it depended on section 115JB applying. No substantial question of law arose, and the Revenue's appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4923