Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
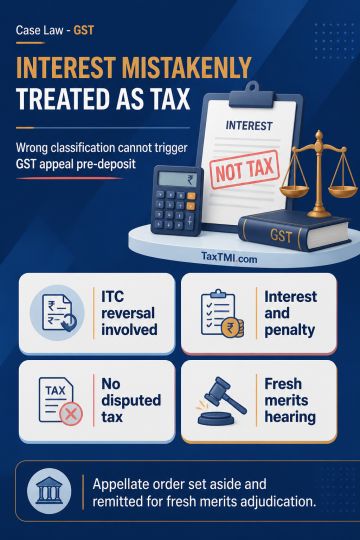
Erroneous classification of interest as tax in Form GST DRC-07 can improperly trigger the statutory pre-deposit required for a further GST appeal. The notes state that the demand for wrong availment and delayed reversal of input tax credit comprised ITC reversal, interest and penalty, with no disputed tax component; however, interest was recorded as tax and affirmed in appeal. Although the original order was later rectified, limitation prevented correction of the appellate order. The appellate order was set aside and remitted for fresh merits adjudication because a Tribunal appeal would otherwise require pre-deposit on interest wrongly treated as tax.
Erroneous classification of interest as tax in Form GST DRC-07 can improperly trigger the statutory pre-deposit required for a further GST appeal. The notes state that the demand for wrong availment and delayed reversal of input tax credit comprised ITC reversal, interest and penalty, with no disputed tax component; however, interest was recorded as tax and affirmed in appeal. Although the original order was later rectified, limitation prevented correction of the appellate order. The appellate order was set aside and remitted for fresh merits adjudication because a Tribunal appeal would otherwise require pre-deposit on interest wrongly treated as tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921