Approved gratuity fund provisions remain deductible despite general actual-payment requirements, preventing revision of the allowed gratuity deduction...
Verification of intangible software expenditure and duplicated disallowances requires record-based reassessment before depreciation and income computa...
Cash receipt aggregation requires a single transaction, event or occasion; separate partner capital contributions cannot attract cash-receipt penaltie...
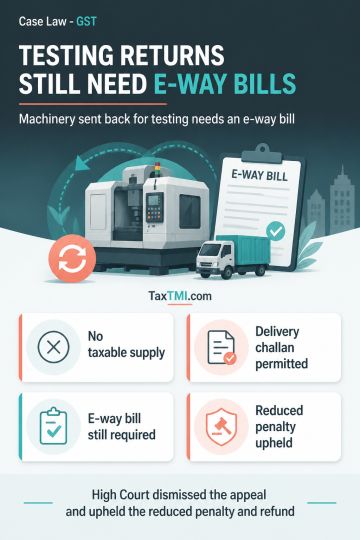
Re-transportation of purchased machinery to the seller for testing without consideration is not a supply under section 7(1)(a) of the CGST/KGST Act and does not attract tax on the movement. Rule 55 permits such movement otherwise than by way of supply under delivery challans, but Rule 138 still requires an e-way bill unless an exemption applies. Transport without the required e-way bill attracts penalty under the second part of section 129(1)(a). The High Court upheld the reduced penalty and consequential refund ordered by the Single Judge, while dismissing the writ appeal.
Re-transportation of purchased machinery to the seller for testing without consideration is not a supply under section 7(1)(a) of the CGST/KGST Act and does not attract tax on the movement. Rule 55 permits such movement otherwise than by way of supply under delivery challans, but Rule 138 still requires an e-way bill unless an exemption applies. Transport without the required e-way bill attracts penalty under the second part of section 129(1)(a). The High Court upheld the reduced penalty and consequential refund ordered by the Single Judge, while dismissing the writ appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925