Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
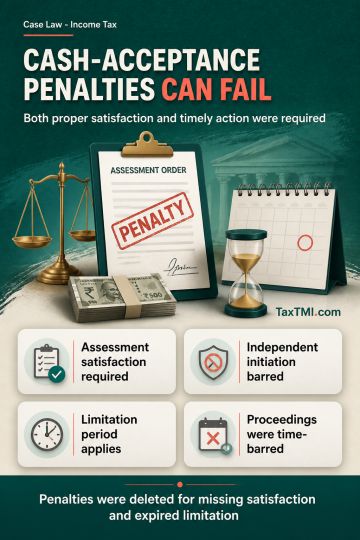
Penalty under section 271D requires the Assessing Officer to record jurisdictional satisfaction during assessment proceedings; without that satisfaction, the Joint Commissioner cannot independently initiate penalty proceedings after dropping proceedings under section 271DA, rendering the penalty without jurisdiction. The notes also explain that penalties under sections 271D and 271E remain subject to the prescribed limitation period. Where the limitation period expired before fresh proceedings were initiated, the subsequent penalty proceedings were time-barred. Accordingly, the penalties described in the source were deleted on the independent grounds of absent jurisdictional satisfaction and limitation.
Penalty under section 271D requires the Assessing Officer to record jurisdictional satisfaction during assessment proceedings; without that satisfaction, the Joint Commissioner cannot independently initiate penalty proceedings after dropping proceedings under section 271DA, rendering the penalty without jurisdiction. The notes also explain that penalties under sections 271D and 271E remain subject to the prescribed limitation period. Where the limitation period expired before fresh proceedings were initiated, the subsequent penalty proceedings were time-barred. Accordingly, the penalties described in the source were deleted on the independent grounds of absent jurisdictional satisfaction and limitation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915