Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
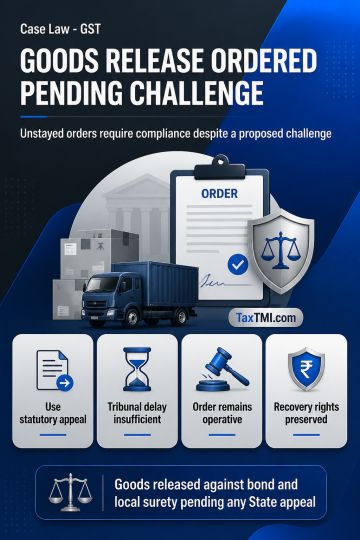
A challenge by the State to a first appellate order under the GST enactment should ordinarily be pursued before the statutory appellate forum, which can examine questions of fact and law; writ jurisdiction should not be exercised at first instance merely because the Tribunal was not fully functional. The appellate order remained operative because it had neither been stayed nor set aside, so compliance could not be withheld on the basis of a proposed challenge. Release of the goods was therefore directed subject to the petitioner furnishing a bond and local surety, preserving consequential recovery if the State ultimately succeeded in appeal.
A challenge by the State to a first appellate order under the GST enactment should ordinarily be pursued before the statutory appellate forum, which can examine questions of fact and law; writ jurisdiction should not be exercised at first instance merely because the Tribunal was not fully functional. The appellate order remained operative because it had neither been stayed nor set aside, so compliance could not be withheld on the basis of a proposed challenge. Release of the goods was therefore directed subject to the petitioner furnishing a bond and local surety, preserving consequential recovery if the State ultimately succeeded in appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913