Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
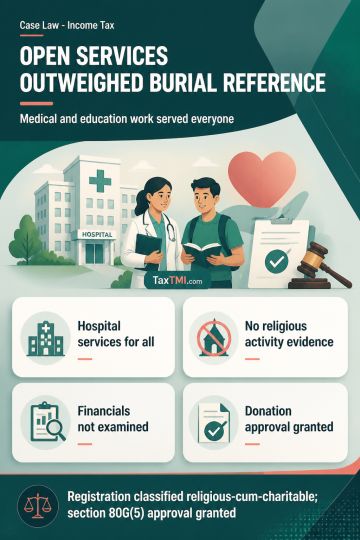
An institution conducting hospital, medical college, education and research activities for persons irrespective of religion, caste or creed should not be treated as purely religious merely because its governing documents contain an isolated reference to churchyards or burial grounds. The described Tribunal decision found no factual evidence of religious activities and held that selective reliance on one object clause, without examining financial statements or actual activities, was insufficient. It directed that the section 12AB registration be classified as religious-cum-charitable and that approval under section 80G(5) be granted, noting that the institution's medical and educational facilities were open to all sections of society and that there was no change in relevant facts.
An institution conducting hospital, medical college, education and research activities for persons irrespective of religion, caste or creed should not be treated as purely religious merely because its governing documents contain an isolated reference to churchyards or burial grounds. The described Tribunal decision found no factual evidence of religious activities and held that selective reliance on one object clause, without examining financial statements or actual activities, was insufficient. It directed that the section 12AB registration be classified as religious-cum-charitable and that approval under section 80G(5) be granted, noting that the institution's medical and educational facilities were open to all sections of society and that there was no change in relevant facts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915