Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
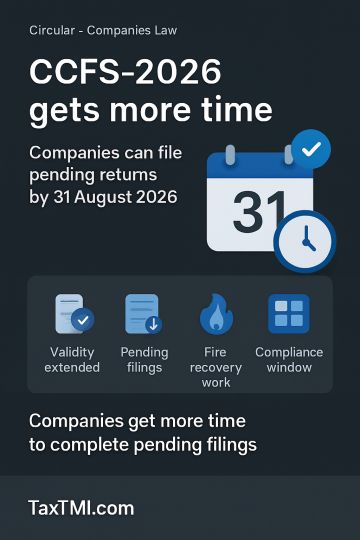
CCFS-2026 has been extended to 31 August 2026, giving companies additional time to complete pending statutory filings under the scheme. The extension was granted because data centre capacity enhancement and restoration work was underway after a fire incident on 5 June 2026. The earlier validity period had been up to 15 July 2026, and the circular simply prolongs the scheme's operative window for compliance completion.
CCFS-2026 has been extended to 31 August 2026, giving companies additional time to complete pending statutory filings under the scheme. The extension was granted because data centre capacity enhancement and restoration work was underway after a fire incident on 5 June 2026. The earlier validity period had been up to 15 July 2026, and the circular simply prolongs the scheme's operative window for compliance completion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916