Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
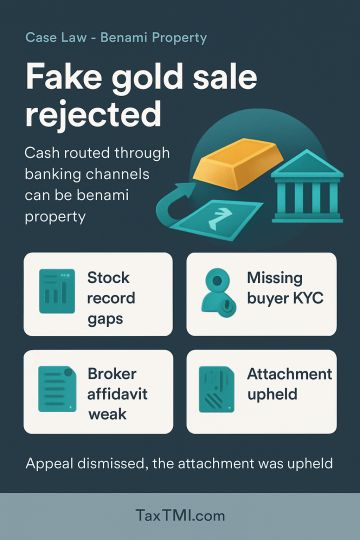
Cash is treated as property under the Act, and routing demonetised cash through another person's bank account and back through banking channels can amount to a benami arrangement if the alleged business deal is not genuine. The Tribunal relied on inconsistencies in stock records, invoices, bank entries and the claimed gold sale, and noted the absence of purchaser KYC, PAN and reliable proof of delivery through the broker; it treated the broker's affidavit as insufficient. It also rejected objections on non-examination of the alleged account operator and on cross-examination, finding the person untraceable and no prejudice shown. The attachment was upheld and the appeal dismissed.
Cash is treated as property under the Act, and routing demonetised cash through another person's bank account and back through banking channels can amount to a benami arrangement if the alleged business deal is not genuine. The Tribunal relied on inconsistencies in stock records, invoices, bank entries and the claimed gold sale, and noted the absence of purchaser KYC, PAN and reliable proof of delivery through the broker; it treated the broker's affidavit as insufficient. It also rejected objections on non-examination of the alleged account operator and on cross-examination, finding the person untraceable and no prejudice shown. The attachment was upheld and the appeal dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916