Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
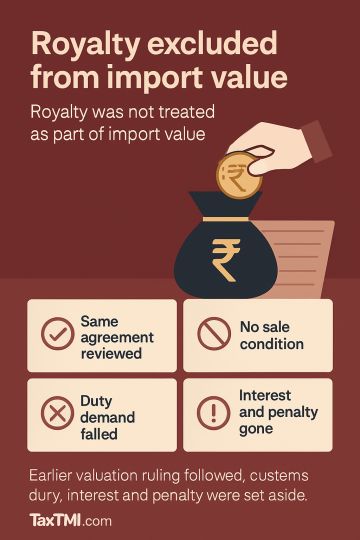
Royalty added to the transaction value of imported raw materials was held unsustainable where the same Technology Assistance Agreement had already been examined in the assessee's own case and the royalty was not shown to be a condition of sale of the imported goods. In the absence of any change in facts, documents, or law, the earlier valuation ruling was followed and the demand for differential customs duty could not be sustained. The consequential interest and penalty were also set aside, with relief allowed accordingly.
Royalty added to the transaction value of imported raw materials was held unsustainable where the same Technology Assistance Agreement had already been examined in the assessee's own case and the royalty was not shown to be a condition of sale of the imported goods. In the absence of any change in facts, documents, or law, the earlier valuation ruling was followed and the demand for differential customs duty could not be sustained. The consequential interest and penalty were also set aside, with relief allowed accordingly.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915