Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Page of 4916
Press 'Enter' after typing page number.
41 to 60 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
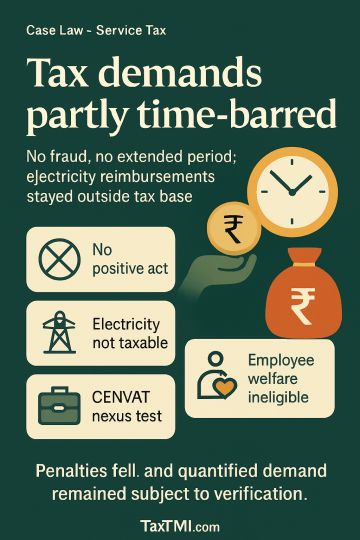
Extended period of limitation could not be invoked on mere non-disclosure in returns; absent a positive act showing fraud, wilful misstatement or deliberate suppression, the demands on sub-lease rent and the related CENVAT credit were held time-barred and the penalties fell with them. Reimbursement of actual electricity charges based on units consumed was not consideration for the renting service and the tax demand on that component was set aside on merits. For CENVAT credit, the governing test was real and sufficient nexus with the output service, while services primarily for personal use or employee welfare were ineligible; the notice-vagueness challenge failed for want of demonstrated prejudice, and the quantified demand was left for verification before recovery.
Extended period of limitation could not be invoked on mere non-disclosure in returns; absent a positive act showing fraud, wilful misstatement or deliberate suppression, the demands on sub-lease rent and the related CENVAT credit were held time-barred and the penalties fell with them. Reimbursement of actual electricity charges based on units consumed was not consideration for the renting service and the tax demand on that component was set aside on merits. For CENVAT credit, the governing test was real and sufficient nexus with the output service, while services primarily for personal use or employee welfare were ineligible; the notice-vagueness challenge failed for want of demonstrated prejudice, and the quantified demand was left for verification before recovery.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916