Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
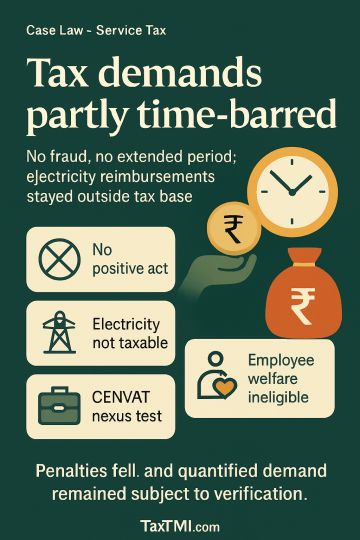
Extended period of limitation could not be invoked on mere non-disclosure in returns; absent a positive act showing fraud, wilful misstatement or deliberate suppression, the demands on sub-lease rent and the related CENVAT credit were held time-barred and the penalties fell with them. Reimbursement of actual electricity charges based on units consumed was not consideration for the renting service and the tax demand on that component was set aside on merits. For CENVAT credit, the governing test was real and sufficient nexus with the output service, while services primarily for personal use or employee welfare were ineligible; the notice-vagueness challenge failed for want of demonstrated prejudice, and the quantified demand was left for verification before recovery.
Extended period of limitation could not be invoked on mere non-disclosure in returns; absent a positive act showing fraud, wilful misstatement or deliberate suppression, the demands on sub-lease rent and the related CENVAT credit were held time-barred and the penalties fell with them. Reimbursement of actual electricity charges based on units consumed was not consideration for the renting service and the tax demand on that component was set aside on merits. For CENVAT credit, the governing test was real and sufficient nexus with the output service, while services primarily for personal use or employee welfare were ineligible; the notice-vagueness challenge failed for want of demonstrated prejudice, and the quantified demand was left for verification before recovery.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915