Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
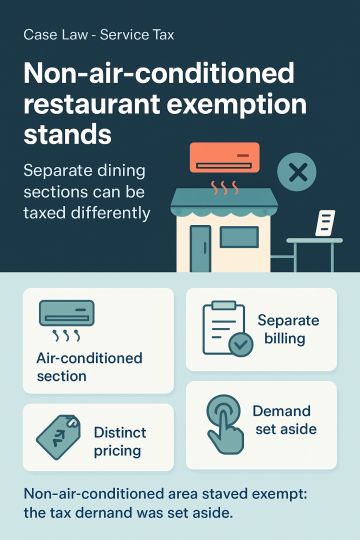
Exemption for non-air-conditioned restaurant services survives where the establishment's air-conditioned section is separately identifiable and taxable.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Service tax on food and beverages served in a non-air-conditioned restaurant area was treated as outside the levy where the same establishment also contained an air-conditioned section. The exemption entry under Notification No. 25/2012-ST, as amended, was read in light of the levy's original focus on air-conditioned restaurants, supported by contemporanea exposition and the Board's clarification. Physical demarcation, separate billing, different pricing and distinct operation showed two severable restaurant services despite a common kitchen, so the non-air-conditioned area remained exempt and the demand was set aside.
Service tax on food and beverages served in a non-air-conditioned restaurant area was treated as outside the levy where the same establishment also contained an air-conditioned section. The exemption entry under Notification No. 25/2012-ST, as amended, was read in light of the levy's original focus on air-conditioned restaurants, supported by contemporanea exposition and the Board's clarification. Physical demarcation, separate billing, different pricing and distinct operation showed two severable restaurant services despite a common kitchen, so the non-air-conditioned area remained exempt and the demand was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918