Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
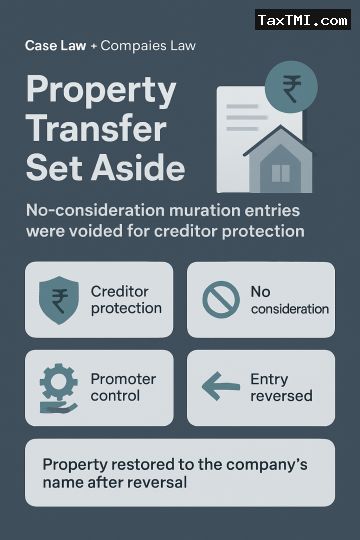
Section 531(1) protects creditors against transfers made within the statutory period as a fraudulent preference, and it can apply even where no formal conveyance is executed if title is effectively shifted through mutation entries. A company's immovable property was entered in the names of its promoters, who controlled the company, without disclosed consideration, valuation, or material supporting any quantified liability said to be owed to them. The absence of consideration and supporting records negatived good faith and showed an attempt to place the property beyond the reach of creditors. The transfer was declared void, and the mutation entries were directed to be reversed so the property stands restored in the company's name.
Section 531(1) protects creditors against transfers made within the statutory period as a fraudulent preference, and it can apply even where no formal conveyance is executed if title is effectively shifted through mutation entries. A company's immovable property was entered in the names of its promoters, who controlled the company, without disclosed consideration, valuation, or material supporting any quantified liability said to be owed to them. The absence of consideration and supporting records negatived good faith and showed an attempt to place the property beyond the reach of creditors. The transfer was declared void, and the mutation entries were directed to be reversed so the property stands restored in the company's name.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI