Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
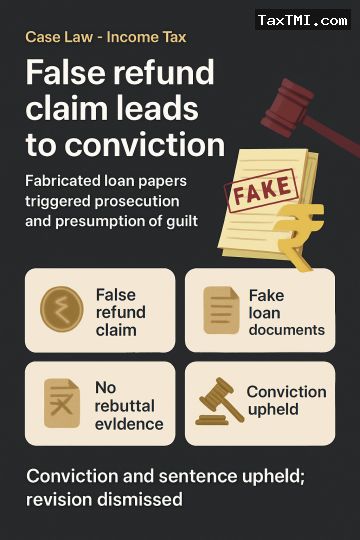
A false refund claim in an income-tax return, supported by fabricated housing-loan documents, attracted prosecution under Section 277. The evidence of the complainant and bank officer proved that the claimed loan documents were false and that no housing loan existed in the taxpayer's name. Once the false statement in the return was established, Section 278E required a presumption of culpable mental state, which was not rebutted because no defence evidence was led and the explanation to the notice was rejected. The concurrent findings were found free from legal infirmity, so the conviction, sentence, and revision dismissal were upheld.
A false refund claim in an income-tax return, supported by fabricated housing-loan documents, attracted prosecution under Section 277. The evidence of the complainant and bank officer proved that the claimed loan documents were false and that no housing loan existed in the taxpayer's name. Once the false statement in the return was established, Section 278E required a presumption of culpable mental state, which was not rebutted because no defence evidence was led and the explanation to the notice was rejected. The concurrent findings were found free from legal infirmity, so the conviction, sentence, and revision dismissal were upheld.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915