Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
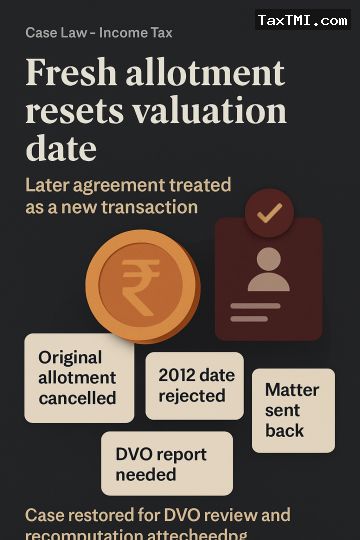
Cancellation of the original allotment and a subsequent fresh allotment to a different flat broke the link with the 2012 transaction; the later registered agreement was treated as a new transaction, so adoption of the earlier valuation date was rejected. The cited precedent was distinguished on facts, and the claim to use the 2012 allotment date for stamp duty valuation was not accepted. On the alternative issue, once the stamp valuation adopted by the authority was disputed and supporting valuation material was filed, the Assessing Officer was required to obtain a DVO report before making any addition. The matter was restored for DVO reference and recomputation after hearing.
Cancellation of the original allotment and a subsequent fresh allotment to a different flat broke the link with the 2012 transaction; the later registered agreement was treated as a new transaction, so adoption of the earlier valuation date was rejected. The cited precedent was distinguished on facts, and the claim to use the 2012 allotment date for stamp duty valuation was not accepted. On the alternative issue, once the stamp valuation adopted by the authority was disputed and supporting valuation material was filed, the Assessing Officer was required to obtain a DVO report before making any addition. The matter was restored for DVO reference and recomputation after hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918