Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
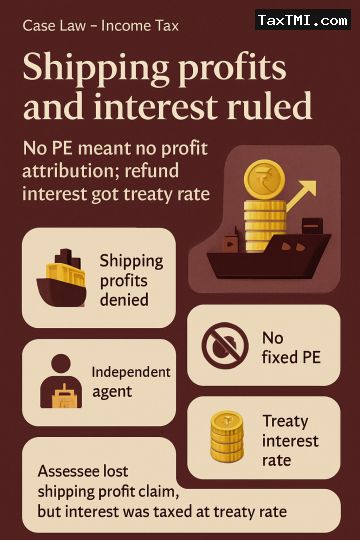
India-Mauritius DTAA treaty shipping profits were denied because the assessee's own earlier years had already been decided against it on the same point, and that consistent view was followed. A fixed place permanent establishment was also not proved: the revenue had to show both disposal of the Indian premises and business activity through them, but the survey material showed only limited visits, agent-led operations, and no controlled space or real use by the non-resident. The Indian agent was treated as independent, so no dependent agent permanent establishment arose. As no PE existed, profit attribution to any alleged PE and aggregation of the two entities' income failed. Refund interest was taxed at the treaty rate under the interest article.
India-Mauritius DTAA treaty shipping profits were denied because the assessee's own earlier years had already been decided against it on the same point, and that consistent view was followed. A fixed place permanent establishment was also not proved: the revenue had to show both disposal of the Indian premises and business activity through them, but the survey material showed only limited visits, agent-led operations, and no controlled space or real use by the non-resident. The Indian agent was treated as independent, so no dependent agent permanent establishment arose. As no PE existed, profit attribution to any alleged PE and aggregation of the two entities' income failed. Refund interest was taxed at the treaty rate under the interest article.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918