Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
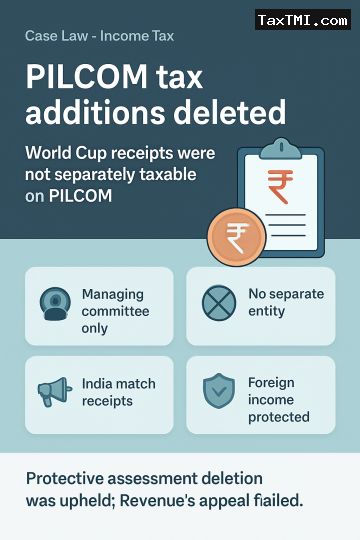
PILCOM was treated as only a managing committee for the World Cup, not an independent assessable entity or association of persons, so the protective additions could not stand. The Tribunal held that receipts and relating to matches in India, and the common receipts already covered in the assessee's accounts and return under the agreed financial arrangement, could not be separately taxed again in PILCOM's hands. It also held that amounts linked to matches outside India were not taxable on a protective basis where the assessee neither received nor was entitled to receive them. The Revenue's appeal failed and the deletion of the protective assessment was upheld.
PILCOM was treated as only a managing committee for the World Cup, not an independent assessable entity or association of persons, so the protective additions could not stand. The Tribunal held that receipts and relating to matches in India, and the common receipts already covered in the assessee's accounts and return under the agreed financial arrangement, could not be separately taxed again in PILCOM's hands. It also held that amounts linked to matches outside India were not taxable on a protective basis where the assessee neither received nor was entitled to receive them. The Revenue's appeal failed and the deletion of the protective assessment was upheld.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916