Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Page of 4905
Press 'Enter' after typing page number.
741 to 760 of 98083 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
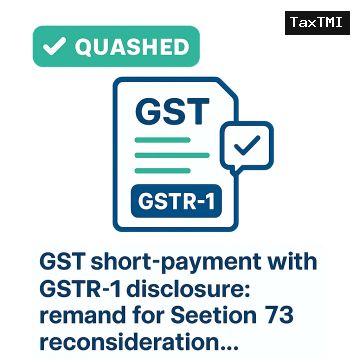
In a GST short-payment dispute, the HC noted that once outward supply was correctly disclosed in GSTR-1, the corresponding tax still had to be paid in GSTR-3B for the relevant period, so mere invocation of the stricter provision did not by itself warrant interference. After considering the later amnesty framework and the GST Council material, the Court treated the matter as one arising from return-filing glitches and admitted-liability mismatch capable of examination under the lesser provision. The demand and penalty order was quashed and the matter remitted for fresh consideration.
In a GST short-payment dispute, the HC noted that once outward supply was correctly disclosed in GSTR-1, the corresponding tax still had to be paid in GSTR-3B for the relevant period, so mere invocation of the stricter provision did not by itself warrant interference. After considering the later amnesty framework and the GST Council material, the Court treated the matter as one arising from return-filing glitches and admitted-liability mismatch capable of examination under the lesser provision. The demand and penalty order was quashed and the matter remitted for fresh consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905