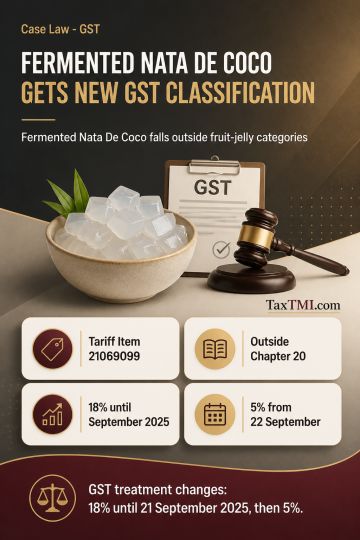
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Under the GST law, proceedings initiated in the name of a deceased assessee were not invalidated where the death had not been intimated to the department. The HC further noted that, even if recourse to the extended limitation under Section 74 was unavailable, proceedings under Section 73 could still be maintained because of the limitation extensions under Section 168A and the Supreme Court's exclusion of limitation in Re: Cognizance; objections based on absence of Section 74 ingredients and limitation were rejected. The Court also affirmed that a legal representative is liable, out of the estate, for tax dues of the deceased, but set aside the ex parte assessment orders and remitted the matters for fresh adjudication on merits.
Under the GST law, proceedings initiated in the name of a deceased assessee were not invalidated where the death had not been intimated to the department. The HC further noted that, even if recourse to the extended limitation under Section 74 was unavailable, proceedings under Section 73 could still be maintained because of the limitation extensions under Section 168A and the Supreme Court's exclusion of limitation in Re: Cognizance; objections based on absence of Section 74 ingredients and limitation were rejected. The Court also affirmed that a legal representative is liable, out of the estate, for tax dues of the deceased, but set aside the ex parte assessment orders and remitted the matters for fresh adjudication on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913