 TaxTMI





 05 Nov 2026

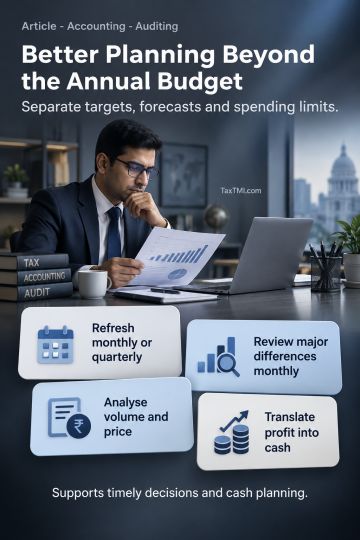
Beyond the April Budget: Rolling Forecasts and Driver Models Every FP&A Adviser Should Introduce
A budget approved in spring and opened again next spring isn't a plan. It's a forecast nobody believes - and a missed chance for the finance function to steer.
In the early 1970s a Swedish bank did something that sounded reckless: under chief executive Jan Wallander, Svenska Handelsbanken scrapped traditional annual budgets altogether.
Wallander's view was that budgets were obvious, wrong or harmful - they encouraged negotiation games, slowed reactions to change and created a false sense of control. In their place the bank used decentralised decisions, rolling forecasts and close comparisons of performance across branches.
For decades afterwards Handelsbanken was often cited as one of Europe's more consistently profitable and resilient banks, and its story became a founding case of the "Beyond Budgeting" movement.
The point isn't that every business should abolish its budget. It's that a budget written once and never challenged does more harm than good.
The yearly ritual
In thousands of businesses the routine repeats itself. Departments are asked for numbers. Sales submits targets that look bold but are safely beatable. Operations pads its cost estimates. Someone adds 10% across the board. The owner trims a few lines, and the budget is approved - and filed.
Two months later a key customer leaves, raw-material prices spike and a competitor cuts prices. Nobody reopens the budget. At year-end everyone compares actuals with a plan that stopped being relevant ten months earlier.
Lesson from history: the navigator
Before satellite navigation, sailors relied on dead reckoning: plot a course, then keep correcting it as speed, wind and current were measured. No navigator fixed a heading at the harbour and refused to alter it for the whole voyage.
Budgets should work the same way. The plan is the starting point; navigation is what keeps the ship off the rocks.
Five myths that keep budgets useless
Myth 1: "The budget is the target."
A budget can serve as a target, a forecast or a spending limit. Ask one number to do all three and people game it - sales lowers targets to beat them, departments inflate costs to protect spending.
Myth 2: "Last year plus 10% is a plan."
Incremental budgeting carries last year's inefficiencies forward and ignores what's changed.
Myth 3: "Once approved, it can't change."
The world moves. A plan that can't respond becomes ceremony.
Myth 4: "Variances are the accountant's problem."
A variance report nobody discusses is just arithmetic.
Myth 5: "Small businesses don't need budgets."
With less room for error, small firms need simple planning more than large ones.
A budget isn't a prophecy. It's a hypothesis about performance - and hypotheses exist to be tested.
The Three-Number Rule
The most useful single change is to stop asking one figure to do three jobs. Under the Three-Number Rule:
| Number | Purpose | Example |
|---|---|---|
| Target | Ambition - what we're reaching for | "We aim for Rs. 12 crore revenue." |
| Forecast | Expectation - what we honestly think will happen | "We currently expect Rs. 10.5 crore." |
| Limit | Permission - what we may spend | "Marketing may spend up to Rs. 60 lakh unless leads beat plan." |
Separate the three and gaming stops: targets can stretch, forecasts can be candid and limits can flex within rules.
In a nutshell
Essence: split ambition, expectation and permission into three numbers, and planning shifts from negotiation to navigation.
What better planning looks like
1. Driver-based models
Find the handful of drivers that move most of the numbers:
- Retailer: footfall, conversion, average bill, gross margin, rent, staff cost.
- Manufacturer: order volume, price, material cost per unit, yield, capacity use.
- Service firm: billable headcount, utilisation, rate, collection days.
When a driver moves, the forecast updates logically without rebuilding the whole budget.
2. Rolling forecasts
Each month or quarter, refresh the outlook for the next twelve months so the horizon always stays ahead. The question becomes "where are we heading and what should change?" rather than "did we hit budget?"
3. Scenario planning
Prepare at least a base, a downside (revenue down 20%, costs up 15%) and an upside case, deciding in advance what you'd do in each. Panic becomes a plan.
4. Owned variance analysis
Review significant variances monthly with the people responsible, splitting them into:
- Volume - sold more or less.
- Price - sold or bought at a different price.
- Efficiency - used more or fewer resources.
- Timing - happened earlier or later than planned.
5. Tie every plan to cash
Profit forecasts must become cash forecasts covering debtors, stock, capex, loan repayments and taxes.
Illustration
A service firm budgets Rs. 6 crore of revenue assuming 40 billable staff at 70% utilisation. By July utilisation is 62% and two senior people have resigned.
Old reflex: "We're behind budget - push harder."
Driver approach: on current drivers the revenue forecast drops to roughly Rs. 5.2 crore, and leadership sees exactly why - utilisation and headcount. They replace one senior hire, redeploy two staff from an unprofitable account and defer an office expansion until utilisation recovers. The target stays ambitious, the forecast stays honest and the limit on new spending tightens.
Same firm, same bad news. One response is frustration; the other is a plan.
For practitioners: building the planning service
- Start from the client's real drivers. Pull volumes, prices and headcount from billing, GST returns and payroll rather than inventing top-down growth rates.
- Keep bank projections honest. CMA data and lender projections should reconcile to the internal forecast; inflated bank numbers produce covenants the client can't meet.
- Run a monthly variance pack. One page per department, with volume, price, efficiency and timing splits and a named owner for each explanation.
- Model statutory cost changes. Factor in labour-code wage definitions, GST rate changes and advance-tax instalments when reforecasting.
- Offer it as a virtual-CFO retainer. A quarterly reforecast meeting is a natural, recurring advisory product for SME clients.
The uncomfortable reality
Many businesses don't fail for want of planning. They fail because their plans are performances - produced to satisfy a bank, investor or board and never used to steer.
A plan that doesn't change behaviour is just paperwork.
Indicators of success
- Monthly variance reviews happen with department heads, not only finance.
- Forecast accuracy improves as rolling forecasts converge on actuals.
- Decisions change because of variances - spending paused, prices adjusted, investments advanced.
- Targets stay stretching but credible - teams don't abandon them by mid-year.
Outlook: the coming decade
Annual budgets are giving way to rolling forecasts, scenario models and driver-based planning, increasingly fed by AI that updates outlooks from live sales, cost and market data. Volatile tariffs, interest rates and input costs make fixed annual plans ever less reliable. Businesses that plan well will treat the budget as a year-long conversation, not a document signed once.
Immediate actions by role
- CEO: ask for three numbers - target, expected and minimum - for revenue, profit and cash.
- CFO: introduce a simple rolling forecast covering the next four quarters.
- Department heads: explain last month's biggest variance and what you'll do about it.
- Board: review the minimum case, not only the target.
Illustration from a smaller enterprise
Take an illustrative owner of a Rs. 12 crore printing business who prepares a budget each April and never opens it again. Paper prices climb 18% in the second quarter, yet selling prices stay unchanged until December.
A simple monthly variance review would have flagged the rise within weeks. The following year the owner compares budget with actuals monthly and adds a price-revision clause to major contracts. Margins hold when paper prices rise again.
Why budgets fail quietly
Budgets rarely collapse dramatically. They fade once nobody looks after April. A budget not compared with reality every month isn't a plan - it's a wish saved in a spreadsheet.
The objection we hear most - and our response
The objection: "Lenders and investors want an annual budget. Rolling forecasts and scenarios sound like extra work for a small finance team."
The answer: Keep the annual budget - it's a useful baseline and often mandatory. Add a light rolling forecast built on five to ten drivers, refreshed quarterly; for a small business it fits in one spreadsheet and takes a few hours a quarter. The effort is modest, the benefit - seeing problems months sooner - is large, and lenders generally trust businesses more when forecasts are candid and current.
A planning rhythm for SMEs
- Annually: priorities, annual budget, key investments, financing needs.
- Quarterly: reforecast the next four quarters; review strategy and major initiatives.
- Monthly: actuals versus budget and forecast, top variances, updated cash forecast.
- Weekly: cash, collections and urgent payments.
Tools and judgement
Spreadsheets remain the most common planning tool and work well when carefully structured; planning software and AI forecasting can analyse patterns, seasonality and drivers at scale. But a model is only as good as its assumptions and the discipline around it - a sophisticated tool producing a budget nobody reviews is no better than a spreadsheet nobody reviews.
Practitioners' FAQ
"Budget versus forecast - what's the difference?"
A budget is a plan set at the start of the year; a forecast is an updated estimate of what will actually happen.
"How often should budgets be reviewed?"
Monthly against actuals, with a rolling forecast refreshed at least quarterly.
"Should managers set their own budgets?"
They should contribute, with leadership challenge, so targets are realistic and owned.
Position as at October 2026: For Indian businesses, planning assumptions now need to reflect the new Income-tax Act (from April 2026), the labour codes' wage definition (which can raise statutory contribution costs), GST rate changes from September 2025 and current RBI policy rates. Revisit these assumptions in every quarterly reforecast.
Pitfalls
- Budgets built by finance alone without operational input.
- Targets nobody believes.
- Rewarding people for beating budgets they lowered.
- Profit plans that ignore cash.
- Models so detailed they take weeks to update.
Terms explained
- Variance - the gap between budgeted and actual results.
- Rolling forecast - an outlook refreshed regularly, always covering the next several months or quarters.
- Driver-based planning - building plans from the few factors that drive results, such as volume, price and headcount.
- Minimum case - the lowest realistic outcome the business must be able to survive.
Half-hour action exercise
1. List the five drivers that most affect results.
2. Note the value assumed in the budget and last month's actual for each.
3. Recalculate full-year revenue and profit on current driver values.
That's a first rolling forecast. Then write Target, Forecast and Limit as three separate numbers - and share all three with the team.
Summary for busy professionals
- Annual budgets fail when written once, used simultaneously as target, forecast and limit, and never revisited.
- Apply the Three-Number Rule: Target (ambition), Forecast (expectation), Limit (permission).
- Replace incremental budgets with driver models, rolling forecasts and scenarios.
- Review variances monthly with owners, split by volume, price, efficiency and timing.
- Always convert profit plans into cash plans.
Plans earn their keep when they're questioned. They become dangerous when trusted blindly.
References
- Jeremy Hope and Robin Fraser, Beyond Budgeting: How Managers Can Break Free from the Annual Performance Trap (Harvard Business School Press, 2003).
- Jan Wallander, Decentralisation - Why and How to Make It Work: The Handelsbanken Way (SNS Fo rlag, 2003).
- Bjarte Bogsnes, Implementing Beyond Budgeting (Wiley, 2nd edition, 2016).
- Michael C. Jensen, "Corporate Budgeting Is Broken - Let's Fix It," Harvard Business Review (November 2001).