Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Case Laws Customs
    Country of Origin Certificates and Preferential Customs Duty under Notification No. 46/2011-Customs ...
    Refund of Accumulated Input Tax Credit on Packing Materials under Section 54(3)(ii) of the CGST Act
    Detention of Goods in Transit: Consequences of Delay in Notice under Section 129(3)
    Case Laws Income Tax
    Section 192 TDS on Leave Travel Concession and the Effect of Subsisting Judicial Restraint
    Cross-Segment Price Manipulation in Stock Derivatives under the SEBI Act and PFUTP Regulations
    Case Laws Income Tax
    Enhanced Rate of Tax u/s 115BBE: Survey Surrenders of Excess Stock and Cash: Business Income, Deemed...
    Retention of Seized Mobile Phones and Bank Debit Cards Beyond the Section 67(7) Period
    Case Laws Customs
    Classification of Disposable Analytical Cartridges under Chapter 90 and Heading 3926
    Reasoned and Speaking Appellate Orders u/s 107 of the CGST Act: Duty to Decide Material Grounds of A...
    Pre-Movement E-Way Bill Compliance and Section 129 Detention for Undocumented Goods in Transit
    Case Laws Income Tax
    Faceless Reassessment Jurisdiction: Retrospective Validation under Section 147A and Automated Alloca...
    Doctrine of Merger: Effect of Non-Speaking and Speaking Dismissal of Special Leave Petitions on Merg...
    Case Laws Indian Laws
    Section 37 of the NDPS Act: Twin Conditions for Grant of Bail in Commercial Quantity Cases
    Case Laws Customs
    Pilferage of Imported Goods: Approval, Custody and Duty Liability under the Customs Act, 1962
    Case Laws Indian Laws
    Condonation of Delay in Statutory Appeals under Section 5 of the Limitation Act, 1963
    Case Laws Income Tax
    Condonation of Delay for Filing Revised Returns under Section 119(2)(b): Genuine Hardship and Merits...
    Case Laws Income Tax
    TDS Credit Where the Deductor Defaults: Proof of Deduction Without Form 16 or Form 16A
    Case Laws Indian Laws
    Reserved High Court Judgments: Constitutional Timelines, Accountability and Litigant Remedies
    Price Depression in Securities Markets: Evidentiary Requirements under the PFUTP Regulations
    Case Laws Income Tax
    Foreign Leave Travel Concession and Tax Deduction at Source under Sections 10(5), 192 and 201
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws Customs
Show AI Summary
Certificate-specific origin verification prevents preferential-duty denial based solely on unrelated suspect certificates or supplier doubts.
Preferential customs-duty treatment requires compliance with applicable rules of origin and reliable proof that imported goods qualify as originating. A country-of-origin certificate is important evidence but does not remove the importer's duty to possess supporting origin information and exercise reasonable care. Challenges to preferential treatment must be certificate-specific and consignment-specific: an adverse finding concerning identified certificates cannot, without direct evidence, invalidate separate certificates. Customs verification should identify the particular proof of origin, alleged defect and material linking it to the import, while fraud, suppression or misrepresentation independently established may support substantive action.
Case Laws GST
Show AI Summary
Packing-material input tax credit may support inverted-duty refunds when higher-rated inputs cause accumulation for taxable packaged supplies.
Refund of accumulated input tax credit under Section 54(3)(ii) may arise where packing materials used to make taxable packaged outward supplies bear a higher tax rate than the outward supply and generate the accumulation. The inquiry extends to all qualifying inputs and is not limited to a principal raw material. Parity between the rate on bulk tea and packaged tea does not itself preclude refund if higher-taxed packing materials used for the packaged supply are the cause of unutilised credit.
Case Laws GST
Show AI Summary
Mandatory detention timelines require timely notice, hearing and penalty order, preventing prolonged restraint of goods in transit.
Section 129(3) establishes a mandatory two-stage timeline: issuance of the penalty notice within seven days of formal detention or seizure, followed by a penalty order within seven days of legally effective service. The periods are independent, and compliance at one stage cannot cure delay at the other. Service, portal timestamps and the electronic records required under Rule 142 are material to chronology. Penalty requires a hearing, while payment under protest may still require a reasoned order to preserve appellate access. Later confiscation action cannot ordinarily cure a defective detention adjudication.
Case Laws Income Tax
Show AI Summary
Subsisting judicial restraint on leave travel concession withholding prevents employer default while preserving employees' underlying tax liability.
A subsisting judicial restraint expressly prohibiting deduction from leave travel concession reimbursements governs the employer's withholding conduct for the covered period. Non-deduction in compliance with that restraint cannot constitute failure to discharge an enforceable duty under Sections 192 and 201, even if the underlying exemption claim is later found substantively unavailable. The restraint does not eliminate employee-level tax liability. For unprotected periods, foreign-leg or circuitous travel claims remain outside the domestic-travel condition, and payer protection may depend on proving employee return filing, income inclusion and tax payment through Form 26A.
Case Laws SEBI
Show AI Summary
Cross-segment price manipulation examines whether futures orders artificially influence option executions, engaging anti-fraud rules, director responsibility, and interim safeguards.
Cross-segment price manipulation may arise where aggressive futures orders alter the last traded price or visible order-book conditions so that larger, sentimentally opposite options orders obtain favourable execution. The relevant inquiry considers the integrated sequence of resting orders, aggressive executions, cancellations, timing, concentration, price impact and delta-adjusted exposure. Anti-fraud prohibitions cover manipulative devices, false appearances of trading and price manipulation, while opposite futures and options positions alone do not establish misconduct. Director liability requires responsibility for business conduct, or consent, connivance or neglect.
Case Laws Income Tax
Show AI Summary
Survey surrender characterisation determines whether excess stock and cash are taxed as business income or under special deemed-income provisions.
The special regime in Section 115BBE is consequential: it applies only after the amount is properly brought within a specified deeming provision, and a survey surrender, book entry or return description cannot itself create that character. Mixed stock forming part of ordinary business inventory and credibly explained through business records may be assessed as business income at normal rates. Similarly, excess cash may be treated as business income where a commercial source is satisfactorily established and no separate or non-business source is shown.
Case Laws GST
Show AI Summary
Statutory limits on GST seizure require return of retained mobile phones and debit cards without a valid extension.
Section 67(7) establishes a six-month return rule where no notice in respect of seized goods is issued. Any further period requires sufficient cause, action by the proper officer, and a maximum further period of six months; ongoing investigation cannot replace an actual extension order. Although Section 67(7) uses "goods" while Section 67(2) also covers documents, books and things, its application to seized mobile phones and bank debit cards indicates that classification cannot be used to avoid the temporal restriction where articles are held under statutory seizure.
Case Laws Customs
Show AI Summary
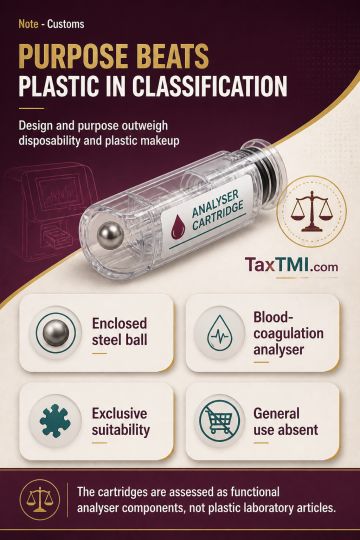
Analytical cartridge classification follows functional integration and sole-use suitability, not plastic composition, disposability, or general consumable character.
STA micro-cuvettes containing an enclosed steel ball are assessed as complete functional components of a blood-coagulation analyser, rather than merely as plastic laboratory articles. Classification turns on their objective design, analytical role, exclusive or principal suitability and absence of practical general use. Chapter 90 Note 2 requires consideration of an independent specific heading first and then classification of other dedicated parts or accessories with the relevant instrument. Disposable or single-use status and plastic composition do not by themselves establish classification as residual plastic articles.
Case Laws GST
Show AI Summary
Speaking appellate orders require findings on material GST appeal grounds, ensuring fair hearings and meaningful higher review.
Section 107(12) requires a written appellate order identifying material points for determination, deciding them, and giving reasons. Formulaic confirmation of original assessment does not establish independent appellate consideration, particularly where jurisdiction, notice, evidence, quantification, taxability, section 74 conditions, interest, or penalty are contested. Sections 74 and 75 require a defined notice, disclosure of relied-upon material, effective hearing, and reasoned determination within the notice's scope. Where procedural defects arise at the original stage as well as on appeal, reconsideration must occur at the level capable of curing the foundational defect without expanding the show-cause case.
Case Laws GST
Show AI Summary
Pre-movement e-way bill compliance requires invoices and transport records before dispatch, while later documents cannot cure undocumented transit.
Pre-movement e-way bill compliance requires issuance of an invoice at or before removal, generation of the e-way bill before road movement, and carriage of both records during transit. Where goods are intercepted without either record, the contravention arises upon commencement of undocumented movement; documents generated only after interception cannot retrospectively establish compliance. Such documents may still be considered with other contemporaneous evidence when assessing bona fides or alleged intent to evade tax. Section 129 detention proceedings remain subject to notice, hearing, electronic-summary and statutory-timeline requirements.
Case Laws Income Tax
Show AI Summary
Automated allocation in reassessment determines officer jurisdiction, while retrospective validation cannot bypass continuing faceless-scheme requirements.
Section 151A and the e-Assessment of Income Escaping Assessment Scheme, 2022 require covered reassessment functions and section 148 notice issuance through automated allocation. Risk-based selection of cases is distinct from randomised allocation of the officer authorised to act. Sections 148A and 148 form an integrated reassessment sequence, so general concurrent jurisdiction, administrative instructions or digital service cannot substitute for the prescribed faceless allocation. Section 147A did not amend the continuing statutory and scheme-based allocation requirements and is treated as constitutionally invalid.
Case Laws GST
Show AI Summary
Doctrine of merger distinguishes refusal of special leave from appellate disposal, preserving review subject to independent procedural limits.
Under Article 136, a refusal of special leave remains a discretionary leave-stage determination. A non-speaking dismissal does not merge the challenged lower-court decision into a Supreme Court order, affirm its reasoning, or automatically create res judicata. A speaking refusal may bind only as to legal propositions expressly declared under Article 141, without producing merger. Merger arises when leave is granted and appellate jurisdiction is exercised. Review, writ, and remanded proceedings remain subject to independent procedural requirements, including limitation and safeguards against abuse.
Case Laws Indian Laws
Show AI Summary
NDPS commercial-quantity bail requires independent proof of non-guilt and low reoffending risk alongside proportionate safeguards.
Section 37 of the NDPS Act imposes cumulative bail conditions in commercial-quantity cases: the court must find reasonable grounds to believe the accused is not guilty and unlikely to reoffend while on bail. These requirements supplement ordinary bail factors and demand a genuine, provisional assessment of credible material. Personal liberty and trial delay remain relevant, but must be reconciled with the statutory threshold. Bail conditions, including verification safeguards for foreign nationals, must be proportionate, genuine and capable of enforcement.
Case Laws Customs
Show AI Summary
Approved customs custodians bear duty for proven pilferage during custody, but not for losses before their approval takes effect.
Customs-duty liability for pilfered imported goods arises only where pilferage occurs after unloading in a customs area while goods are held by an approved custodian. Approval is indispensable; factual control or statutory custody alone does not impose this liability for a period before approval. Importer duty exemption for pre-clearance pilferage operates alongside the custodian's revenue liability. Pilferage must be proved through contemporaneous records and cannot be presumed from every cargo discrepancy, shortage, or loss.
Case Laws Indian Laws
Show AI Summary
Condonation of delay under Section 5 remains available in special statutory appeals unless the governing scheme clearly excludes it.
Section 5 of the Limitation Act, 1963 applies to a special statutory appeal through Section 29(2) unless the governing enactment excludes it expressly or by necessary implication. A special limitation period alone is insufficient to exclude condonation. Restrictive language, a defined maximum condonable period, or a complete statutory limitation code may create a non-extendable outer limit. Section 9 of the Chhattisgarh Rajya Suraksha Adhiniyam contains a 30-day appeal period and excludes certified-copy time, but lacks an express bar or outer condonation ceiling; delay may therefore be considered upon proof of sufficient cause.
Case Laws Income Tax
Show AI Summary
Genuine hardship in delayed revised-return claims requires prima facie verification without converting condonation into final tax adjudication.
Section 119(2)(b) may permit admission of a delayed revised-return claim where expiry of the Section 139(5) period causes genuine hardship. Condonation removes only the procedural bar and does not establish exemption, refund, or interest entitlement. Genuine hardship requires assessment of bona fides, the nature of the omission, promptness after discovery, legal plausibility, and the consequence of refusal. Circular No. 9/2015 permits prima facie verification and inquiry, but substantive taxability and refund entitlement remain for merits examination.
Case Laws Income Tax
Show AI Summary
TDS credit after verified deduction protects taxpayers from demands and refund adjustments caused by deductor default.
TDS credit in domestic deductor-default cases depends on verified actual deduction from the taxpayer's income, not solely on deposit, TDS statements, Form 16 or Form 16A, or Form 26AS reflection. Section 205 bars direct or indirect recovery, including refund adjustment, to the extent tax was deducted. The taxpayer must provide reliable payment-specific evidence, and the Assessing Officer must verify the claim while the Department proceeds against the defaulting deductor.
Case Laws Indian Laws
Show AI Summary
Timely reserved judgments: a three-month framework, transparency, and staged remedies protect liberty and require reasoned decisions.
Reserved High Court judgments are subject to a three-month framework for a reasoned pronouncement, supported by monthly monitoring, status disclosures, date-recorded certified copies, and automated notice to advocates. Urgent matters may receive an operative-part pronouncement, but reasons must be uploaded within seven days or, where practical difficulties exist, within fifteen days. Parties may seek early pronouncement after the specified period and, after further delay, request withdrawal and assignment for a fresh hearing.
Case Laws SEBI
Show AI Summary
Settlement-price depression allegations require cogent proof of manipulation, not merely short exposure, closing sales, or position-limit non-disclosure.
Settlement-price depression under the PFUTP framework requires cogent proof of a manipulative act, device, scheme or artifice, not merely a substantial short derivative position, closing-window sales, or an incentive to benefit from a lower settlement price. Position concentration and position-limit non-disclosure are distinct from PFUTP fraud. Sales below the last traded price require market-wide causal analysis of other trading activity, execution mechanics, benchmark methodology, commercial rationale, and actual price impact. A genuine hedge and agency-attributed exposure do not, without further proof, establish manipulation.
Case Laws Income Tax
Show AI Summary
Foreign LTC tax exemption requires domestic travel; employers must deduct tax on known non-exempt travel reimbursements.
Foreign LTC/LFC payments for itineraries containing an overseas leg are outside the Section 10(5) exemption, which is confined to actual eligible domestic travel subject to Rule 2B shortest-route and fare conditions. Under Section 192, employers must include known non-exempt payments in estimated salary and deduct tax; they cannot disregard available claim records showing foreign or circuitous travel. A recovery restraint does not automatically suspend the deduction obligation. Section 201 recipient-compliance conditions, interest, and penalty based on reasonable cause require separate analysis.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Introduction of concept of mediation and Advance Ruling System for Residents to reduce tax litigation and more clarity

15 September, 2020

Contents
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

2020 (9) TMI 496 - Supreme Court

While decided an issue pertaining to AY 1976-77, honorable Supreme Court has wrote two postscript with the following note:

We have been persuaded to write two postscripts on account of the backbreaking dockets which are ever increasing and as a move towards a trust between the Tax Department and the assessee, and we hope that both the aspects meet consideration at an appropriate level. [Para 21]


Postscript 1:

1. The Indian legal system is reeling under a docket explosion.

The Government and public authorities are active contributories to this deluge. To top it, a number of litigations arise inter se the Government and its bodies and, thus, the only question, as stated in the beginning, is which pocket of the Government will be benefitted?

2. The aforesaid position resulted in a judicial innovation with the Supreme Court passing orders in Oil and Natural Gas Commission & Anr. v. Collector of Central Excise [1991 (10) TMI 58 - Supreme Court] requiring that such cases must be referred to a Committee to be appointed by the Government to facilitate a resolution of such disputes and that no case should be filed without the approval of this Committee. This system was a failure as is apparent from the facts of the present case, where the SLP filed by the appellant-Corporation was initially dismissed with liberty to revive the same in case the High Powered Committee granted such a permission which was so granted in a meeting held on 14.08.2009. The said Committee discussed the legal ramifications, and in some way opined in favour of the appellant-Corporation, as is apparent from the discussion aforesaid. But the ball was again lobbed back into the Court to adjudicate the said issue rather than a resolution being reached. The result was only the revival of the appeal, and the consequent decision which has seen the light of the day only now.

3. The aforesaid failure of the system resulted in the Supreme Court recalling its orders in the ONGC cases vide Electronics Corporation of India v. Union of India. [2011 (2) TMI 3 - Supreme Court].

4. The Central Government and the State authorities have been repeatedly emphasising that they have evolved a litigation policy. Our experience is that it is observed more in breach. The approach is one of bringing everything to the highest level before this Court, so that there is no responsibility in the decision-making process – an unfortunate situation which creates unnecessary burden on the judicial system. This aspect has also been commented upon in a judgment of this Court in Union of India & Ors. v. Pirthwi Singh & Ors., [2018 (4) TMI 1586 - Supreme Court]   albeit between the Government and the private parties, where the question of law had been settled and yet the appeal was filed only to invite a dismissal. The object appears to be that a certificate for dismissal is obtained from the highest court so that a quietus could be put to the matter in the Government Departments. Undoubtedly, this is complete wastage of judicial time and in various orders of this Court it has been categorized as “certificate cases”, i.e., the purpose of which is only to obtain this certificate of dismissal.

5. The 126th Law Commission of India Report titled ‘Government and Public Sector Undertaking Litigation Policy and Strategies’ debated the Government versus Government matters which weighed heavily on the time of the Courts as well as the public exchequer. This was as far back as in 1988. It was only in the year 2010 that the National Litigation Policy (for short ‘NLP’) was formulated with the aim of reducing litigation and making the Government an efficient and responsible litigant. Five (5) years later it reportedly saw a revision to increase its efficacy, but it has hardly made an impact. In the year 2018, the Central Government gave its approval towards strengthening the resolution of commercial disputes of Central Public Sector Enterprises (for short ‘CPSEs’)/ Port Trusts inter se, as well as between CPSEs and other Government Departments/Organisations. The aim was and is to put in place a mechanism within the Government for promoting a speedy resolution of disputes of this  kind, however it excluded disputes relating to Railways, Income Tax, Customs and Excise Departments. It has now been made applicable to all disputes other than those related to taxation matters. This was pursuant an order passed in The Commissioner of Income Tax (Exemptions) v. National Interest Exchange of India -SLP (C) Diary No. 35567 of 2019 [2020 (3) TMI 1250 - SC ORDER] by a bench of which one of us (Sanjay Kishan Kaul, J.) was a part.

6. Insofar as non-taxation matters are concerned, the Administrative Mechanism for Resolution of CPSEs Disputes was conceptualised to replace the Permanent Machinery of Arbitration and to promote equity through collective efforts to resolve disputes. It has a two-tiered structure.

7. At the first level, commercial disputes will be referred to the Committee comprising Secretaries of the Administrative Ministries/Departments to which the disputing parties belong and the Secretary, Department of Legal Affairs. In case the two disputing parties belong to the same Ministry/Department, the Committee will comprise Secretary of Administrative Ministry/Department concerned; the Secretary, Department of Legal Affairs and the Secretary, Department of Public Enterprises. If a dispute is between a CPSE and a State Government Department/Organisation, the Committee will comprise of the Secretary of the Ministry Department of the Union to which the CPSE belongs, the Secretary, Department of Legal Affairs and the Chief Secretary of the State concerned. Such disputes are ideally to be resolved at the first level itself within a time schedule of three (3) months, and in the eventuality of them remaining unresolved, the same may be referred to the Cabinet Secretary at the second level, whose decision will be final and binding on all concerned.

8. We are of the opinion that one of the main impediments to such a resolution, plainly speaking, is that the bureaucrats are reluctant to accept responsibility of taking such decisions, apprehending that at some future date their decision may be called into question and they may face consequences post retirement. In order to make the system function effectively, it may be appropriate to have a Committee of legal experts presided by a retired Judge to give their imprimatur to  the settlement so that such apprehensions do not come in the way of arriving at a settlement. It is our pious hope that a serious thought would be given to the aspect of dispute resolution amicably, more so in the post-COVID period.

9. In most countries, mediation has proved to be an efficacious remedy and here we are talking about mediation inter se the Government authorities or Government departments. India is now a signatory to the Singapore Convention on Mediation and we understand that a serious thought is being given to bring forth a comprehensive legislation to institutionalise mediation, in furtherance of this function to which India has committed itself.

Postscript 2:

10. We now turn to the issue of matters pertaining to CPSEs and Government authorities insofar as taxation matters are concerned,  because they are consistently sought to be carved out as a separate category of cases. One of the largest areas of litigation for the Government is taxation matters. The petition rate of the tax department before the Supreme Court is at 87%. - See ‘Economic Survey 2017-19 – Volume 1’ by the Department of Economic Affairs, Ministry of Finance, Government of India So, the question is can something be done about it?

11. In our opinion, a vibrant system of Advance Ruling can go a long way in reducing taxation litigation. This is not only true of these kinds of disputes but even disputes between the taxation department and private persons, who are more than willing to comply with the law of the land but find some ambiguity. Instead of first filing a return and then facing consequences from the Department because of a different perception which the Department may have, an Advance Ruling System can facilitate not only such a resolution, but also avoid the tiers of litigation which such cases go through as in the present case. In fact, before further discussing this Advance Ruling System, we can unhesitatingly say that, at least, for CPSEs and Government authorities, there would be no question of taking this matter further once an Advance Ruling is delivered, and even in case of private persons, the scope of any further challenge is completely narrowed down.

12. It is as far back as in 1971 that a report was submitted by the Direct Taxes Enquiry Committee under the Chairmanship of Dr. K.N. Wanchoo, recognising the need for providing Advance Ruling System, particularly in cases involving foreign collaboration. The aim was to give advance rulings to taxpayers or prospective taxpayers, which would then considerably reduce the Revenue’s workload and decrease the number of disputes. This finally resulted in a scheme of Advance Ruling being brought into effect in 1993, with the introduction of a new Chapter in the Income Tax Act, 1961 (hereinafter referred to as the ‘IT Act’). A quasi-judicial tribunal was established as the Authority for Advance Rulings (for short ‘AAR’) to provide certainty and avoid litigation related to taxation of transactions involving non- residents. The scope of the transactions on which an advance ruling can be sought from the AAR has gradually increased to now include both residents and non-residents, who can seek the same for issues having a substantial tax impact. Chapter XIX-B of the IT Act deals with advance rulings and it has been defined in Section 245N(a) of the  IT Act. These rulings are binding both on the Income Tax Department and the applicant, and while there is no statutory right to appeal, the Supreme Court has held in Columbia Sportswear Company v. Director of Income Tax Bangalore [2012 (8) TMI 105 - Supreme Court]  that a challenge an advance ruling first lies before the High Court, and subsequently before the Supreme Court. The advance ruling may be reversed in the event a substantial question of general public importance arises or a similar question is already pending before the Supreme Court for adjudication.

13. The ground level situation is that this methodology has proved to be illusionary because there is an increasing number of applications pending before the AAR due to its low disposal rate and contrary to the expectation that a ruling would be given in six (6) months (as per Section 245R(6) of the IT Act), the average time taken is stated to be reaching around four (4) years!- See Deloitte Report on Advance Rulings in India: Delivering Greater Tax Certainty (Deloitte Tax Policy Paper 5, 2019)  There is obviously lack of adequate numbers of presiding officers to deal with the volume of cases. Interestingly, the primary reason for this is the large number of vacancies and delayed appointments of Members to the AAR. ibid In view of the time taken, the very purpose of AAR is defeated, resulting in the mechanism being used infrequently as is evident from the ever- increasing tax related litigation.

14. We may notice a significant development in Section 245N of the IT Act. It was through Notification No.11456 dated 3.8.2000 that public sector companies were added to the definition of ‘applicant’, and in 2014, it was made applicable to a resident who had undertaken one or more transactions of the value of ₹ 100 crore or more.

15. Insofar as a resident is concerned, the limit is so high that it cannot provide any solace to any individual, and we do believe that it is time to reconsider and reduce the ceiling limit, more so in terms of the recent announcement stated to be in furtherance of a tax friendly face-less regime!

16. We may refer to the international scenario where there has been an incremental shift towards mature tax regimes adopting advance ruling mechanisms. The increase in global trade puts the rulings system at the centre-stage of a robust international tax cooperation regime. The Organisation for Economic Cooperation and Development (for short ‘OECD’) lists advance rulings as one of the indicators to assess trade facilitation policies, making it an aspirational international best practice standard. For example, Australia and New Zealand have a robust system of advance rulings wherein the decisions (which are public rulings affecting a large number of taxpayers) are given teeth by being made binding on the revenue authorities. New Zealand has gone a step further and innovated “status rulings” under which a taxpayer can apply to the Commissioner for a ruling on how a change in the law impacts an existing ruling.

17. In the United States, there is a mechanism for the Treasury to authorise guidance in the form of revenue rulings, procedures and notices. The mechanism again, has been bolstered by subsequent practice and interpretations of the United States courts, where rulings have indicated that taxpayers may be penalised if they act inconsistently with legal interpretations set out in the revenue rulings, procedures or notices.

18. Tax transparency has been a hallmark trait of the Swedish legal system. Swedish law requires public disclosure of ex ante tax administration such as advance rulings. Both the taxpayer as well as the Swedish Tax Agency can request an advance tax ruling, these rulings are published without information identifying the taxpayer that requested them. The Skatterättsnämnden, or the Council for Advance Tax Rulings is the Swedish Government agency which is vested with this power. The advance ruling system has played a crucial role in Sweden’s position as a country with one of the highest tax compliance rates in the world.

19. The aim of any properly framed advance ruling system ought to be a dialogue between taxpayers and revenue authorities to fulfil the mutually beneficial purpose for taxpayers and revenue authorities of bolstering tax compliance and boosting tax morale. This mechanism should not become another stage in the litigation process.

20. We, thus, consider it appropriate to recommend to the Central Government to consider the efficacy of the advance tax ruling system and make it more comprehensive as a tool for settlement of disputes rather than battling it through different tiers, whether private or public sectors are involved. A council for Advance Tax Ruling based on the Swedish model and the New Zealand system may be a possible way forward.


Full Text:

2020 (9) TMI 496 - Supreme Court

Topics

Acts Income Tax