Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    News Bill
    Rationalising due dates for filing of return of Income.
    News Bill
    Extending the period of filing revised return
    News Bill
    Scope of filing of updated return in the case of reduction of losses – reg.
    News Bill
    Allowing the filing of updated return after issuance of notice of reassessment
    News Bill
    Foreign Assets of Small Taxpayers - Disclosure Scheme, 2026 (FAST-DS 2026)
    News Bill
    Relaxation of conditions for prosecution under the Black Money Act
    News Bill
    Rationalization of prosecution proceedings
    News Bill
    Rationalizing the period of block in case of other persons
    News Bill
    Referencing the time limit to complete block assessment to the initiation of search or requisition
    News Bill
    Rationalisation of Penalties into Fee
    News Bill
    Imposition of penalty for under-reporting or misreporting of income within Assessment Order
    News Bill
    ​​​​​​​Increase in maximum amount of penalty in section 46...
    News Bill
    Rationalisation of tax rate under section 195 and penalty under section 443 in respect of certain In...
    News Bill
    Expanding the scope of immunity from penalty or prosecution under section 440 of the Act
    News Bill
    ​​​​​​​Expanding the scope of immunity from imposition of ...
    News Bill
    Deductions in respect of dividends received and distributed by certain cooperative societies
    News Bill
    Widening scope of deduction under section 149 by including ancilliary activities of cattle feed and ...
    News Bill
    Inclusion of Cooperatives registered under Multi-State Cooperative Societies Act, 2002 in the defini...
    News Bill
    Amendment of section 169 of the Income-tax Act, 2025 relating to providing effect to advance pricing...
    News Bill
    Exemption to a foreign company on any income arising in India by way of procuring data centre servic...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
News Bill
Show AI Summary
Due dates for filing income tax returns extended for non-audit businesses, partners and certain trusts to ease compliance.
Rationalisation of due date deadlines restructures filing timelines by class of taxpayer to provide additional time for business or professional assessees whose accounts do not require audit, partners (and specified spouses) and certain trusts. The amendment sets 30 November for one specified class, 31 October for audited entities, 31 August for non audit business cases and partners/spouses in non audit situations, and 31 July for all other assessees, while preserving 31 July for certain individual return forms; parallel explanatory amendments for trusts are enacted and the changes are given prospective effective dates in 2026.
News Bill
Show AI Summary
Revised income-tax returns: filing window extended to 12 months; fee proposed for revisions after nine months.
The proposal increases the time limit for filing a revised income-tax return from nine to twelve months from the end of the relevant tax year to allow those who file belated returns late to still revise returns; a fee is proposed for revised returns filed after nine months, with corresponding amendments and staggered commencement dates across the two income-tax statutes applying to the relevant tax and assessment years.
News Bill
Show AI Summary
Updated tax returns may be allowed when a taxpayer reduces a previously claimed loss, per proposed Finance Bill changes.
Section 263(6) permits an updated return within 48 months but bars updated returns that are returns of loss, limits reductions in tax liability or increases in refund, and restricts filing during or after assessment, reassessment, search, survey or prosecution. The Finance Bill, 2026 proposes to amend section 263(6) to allow filing an updated return where the taxpayer reduces the amount of loss claimed in a duly filed return of loss, and to make parallel amendments to the Income-tax Act, 1961.
News Bill
Show AI Summary
Updated tax returns allowed in response to reassessment notices, with extra tax payable and penalty exclusion for that income.
Permits furnishing an updated return in response to a reassessment notice within the notice period, precludes alternative filing in response to that notice, maintains existing restrictions on updated returns, and requires payment of prescribed additional income tax; where filed in pursuance of the notice an extra 10% of aggregate tax and interest is payable and that income will not form the basis for penalty.
News Bill
Show AI Summary
Foreign asset disclosure scheme for small taxpayers offers a time-bound window with tax/fee and limited immunity.
The proposed FAST-DS 2026 provides a time bound window for small taxpayers to declare undisclosed foreign assets and foreign sourced income, requires payment of tax or a fee based on nature and source of acquisition, and grants limited immunity from penalty and prosecution under the Black Money Act for matters covered by the declaration, while excluding cases involving prosecution or proceeds of crime; the scheme is included in the Finance Bill, 2026 (Clauses 114-128) and will commence from a date notified by the Central Government.
News Bill
Show AI Summary
Relaxation of prosecution under the Black Money Act excludes small-value foreign assets from sections 49 and 50.
The Finance Bill proposes that sections 49 and 50 of the Black Money Act will not apply to foreign assets (other than immovable property) where the aggregate value does not exceed twenty lakh rupees, thereby excluding prosecution for minor or inadvertent nondisclosures and aligning prosecution exposure with the Act's penalty framework; the amendment is to have retrospective effect from 1 October 2024.
News Bill
Show AI Summary
Union Budget 2026 27 proposes decriminalisation of tax offences, replacing rigorous terms with graded simple imprisonment and fines.
Amendments to sections 473-485 and 494 recast many penalties from rigorous to simple imprisonment, cap most maximum terms at two years (with lower terms for subsequent offences), introduce fines in lieu of or alongside imprisonment, and adopt a tiered penalty structure tied to amounts of tax evaded-higher tiers permitting up to two years' simple imprisonment, intermediate tiers up to six months, and lower tiers limited to fines-while fully decriminalising selected offences and creating specific carve outs for certain TDS/TCS categories.
News Bill
Show AI Summary
Union Budget change limits block assessment period for third parties when undisclosed income pertains to a single tax year.
Section 295 currently requires that seized material relating to undisclosed income of a person other than the specified person be handed to that person's AO and that the other person undergo block assessment with the same block period; the Finance Bill proposes amending Section 295(2) to limit the period of block for such third parties, particularly where the undisclosed income pertains to a single tax year, with effect for searches or requisitions initiated on or after 1 April 2026.
News Bill
Show AI Summary
Union Budget 2026-27 proposes using initiation of search as the trigger for block assessment and extending the period to eighteen months.
The amendment replaces the last search authorization date with the initiation of search (or requisition) as the reference for computing the block-assessment limitation period and increases that period from twelve months to eighteen months, effective for searches or requisitions initiated on or after 1 April 2026.
News Bill
Show AI Summary
Penalties for certain compliance failures converted into graded fees with specified caps, effective April 1, 2026.
Select penalties for technical compliance failures are converted into prescribed graded fees: audit-reporting failures replaced by fees of Rs. 75,000 and Rs. 1,50,000 depending on delay; failure to furnish accountant reports for international or specified domestic transactions replaced by fees of Rs. 50,000 and Rs. 1,00,000; and failure to furnish statements of financial transactions or reportable accounts is converted into a fee with an introduced upper limit of Rs. 1,00,000 for the post-notice daily levy. The amendments take effect from the tax year beginning 1 April, 2026.
News Bill
Show AI Summary
Union Budget changes penalty process: under-reporting penalties imposed within assessment order; interest charged post-appeal, effective April 2027.
Penalties for under-reporting or misreporting are to be imposed within the assessment order to avoid multiple proceedings; consequential amendments align penalty, dispute resolution and recovery provisions. Interest under the tax recovery provision will be charged only after an appellate order by the first appellate authority or tribunal in appeals from dispute resolution forum orders.
News Bill
Show AI Summary
Increase in penalty for failing to comply with tax information requests from business premises to strengthen compliance.
Amendment to section 466 raises the maximum penalty for non-compliance with section 254 information directions from Rs. 1,000 to Rs. 25,000, to enhance deterrence and voluntary compliance. The enhanced sanction is to be imposed by specified tax officers and takes effect from 1 April 2026, applying to tax year 2026-27 and subsequent years.
News Bill
Show AI Summary
Tax on unexplained income cut to 30% and penalty treatment moved into the misreporting under reporting regime.
The proposal reduces the special tax charge on income determined as unexplained under sections 102-106 from 60% to 30% by amending section 195 and omits the standalone 10% penalty under section 443, subsuming penalty treatment into the under reporting/misreporting regime of section 439(11); the changes take effect from 1 April 2026 for tax year 2026-27 and thereafter.
News Bill
Show AI Summary
Union Budget expands taxpayer immunity to misreporting cases, allowing settlement by paying additional tax in lieu of penalty.
Section 440 is to be amended to allow immunity from penalty and prosecution where under reporting arises from misreporting, subject to existing eligibility and procedural conditions. Immunity requires payment of additional income tax equal to 100% of the tax on such income; for income determined as unexplained credits/investments/assets the additional tax payable for immunity is 120%. The amendment is effective 1 April 2026 for tax year 2026 27 onward.
News Bill
Show AI Summary
Amendment expands tax immunity to cover under reporting that results from misreporting, subject to existing procedural conditions.
Amendment extends the existing immunity from penalty and prosecution to cases where under reporting of income results from misreporting, subject to existing conditions: payment of tax and interest within the demand period, no appeal against the assessment, timely filing of an immunity application within one month, and assessing officer decision on the application within three months.
News Bill
Show AI Summary
Cooperative societies: deduction allowed on dividends from other cooperatives in new tax regime; limited federal cooperative relief.
Deduction is extended to dividends received by cooperative societies from other cooperative societies in the new tax regime, limited to amounts distributed to members. Notified federal cooperatives may claim a temporary deduction for dividends from companies for three years, restricted to investments made by the federal cooperative on or before 31.01.2026 and distributed to members. The amendment is effective from 1 April 2026 and applies to the tax year 2026-27 and subsequent years.
News Bill
Show AI Summary
Union Budget expands deduction to include cattle feed and cotton seeds under section 149(2)(b) for primary co operative societies.
Amendment expands section 149(2)(b) to permit full deduction of profits and gains of a primary co-operative society where members supply cattle feed and cotton seeds to a federal co-operative society, Government, local authority, Government company, or corporation engaged in the same business, applying from the tax year beginning 1 April 2026.
News Bill
Show AI Summary
Inclusion of multi-state co-operative societies in the co-operative society definition for tax purposes from April 2026.
Amendment expands the statutory definition of co-operative society to expressly include societies registered under the Multi-State Cooperative Societies Act, 2002, thereby bringing multi state registered cooperatives within the legal category subject to provisions applicable to co-operative societies under the Act.
News Bill
Show AI Summary
Advance pricing agreements now allow associated enterprises to file modified returns within three months for covered tax years.
Where income is modified as a result of an advance pricing agreement entered into with any person, that person or any associated enterprise may furnish a return or modified return limited to the agreement, within three months from the end of the month in which the agreement was entered into, in respect of tax years covered by such agreement entered on or after 1 April 2026 for tax years beginning 1 April 2026 and subsequent tax years.
News Bill
Show AI Summary
Exemption for foreign companies on income from procuring data centre services if routed through an Indian reseller.
A foreign company is exempt from Indian tax on income arising from procuring data centre services from a specified data centre, provided services to India users are routed through an Indian reseller; a specified data centre must be set up under an approved scheme notified by the Ministry of Electronics and Information Technology and be owned and operated by an Indian company; the exemption applies from the tax year beginning 1 April 2026 through the tax year ending 31 March 2047.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Subcontracted Services on Own Account and the Intermediary Exclusion under Section 2(13)

6 November, 2026

Contents
Circulars
Acts
Rules & Regulations
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

This is a neutral professional article. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.

2026 (10) TMI 1143 - GSTAT NEW DELHI-[PB]

At a Glance

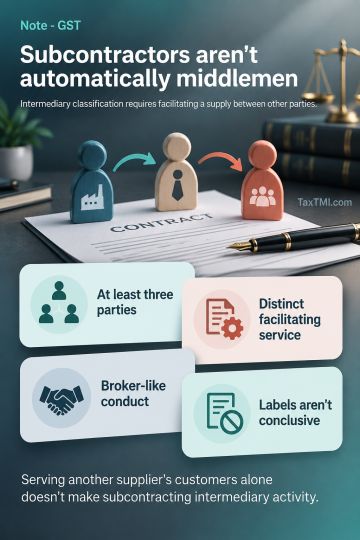
  • A subcontractor actually performing contracted services on its own account is distinguishable from an intermediary merely arranging or facilitating another person's supply.
  • The existence of several participants in a commercial chain does not, by itself, establish intermediary services. The relevant arrangement must disclose a main supply and a separate arranging or facilitating supply.
  • Independent-contractor obligations, responsibility for deliverables, contractual relationships, invoicing and consideration must be examined together. Neither contractual nomenclature nor the remuneration method is conclusive in isolation.
  • Exclusion from intermediary status does not automatically establish an export. All five conditions in Section 2(6) of the Integrated Goods and Services Tax Act, 2017 must be satisfied.

Background & Context

Marketing, recruitment support and customer-facing activities frequently involve interaction with persons other than the contractual recipient. The central classification question is whether the Indian supplier performs an identifiable service for the overseas recipient or merely brings about a supply between other persons.

In 2026 (10) TMI 1143 - GSTAT NEW DELHI-[PB], the taxpayer supplied marketing, promotional, business-support and IT-enabled services to an overseas recipient under a master services agreement. The overseas recipient separately contracted with foreign educational institutions and local recruitment advisers. The advisers interacted with prospective students and received enrolment-linked commission.

The taxpayer's arrangement was different. It received cost-plus remuneration in convertible foreign exchange, operated as an independent contractor and was restricted from undertaking obligations for the overseas recipient without prior written instruction. It was not a party to the advisers' agreements and did not invoice either the educational institutions or the advisers.

The department treated activities such as supporting advisers, liaising with recruitment agents and assisting admission processes as facilitation of education services. Refund claims were consequently rejected. The tribunal instead held that the taxpayer performed subcontracted services on its own account, qualified as an exporter of services and was entitled to refund relief in its appeals.

Key Issues / Provisions

The intermediary definition and its express exclusion

Section 2(13) of the IGST Act defines an intermediary as "a broker, an agent or any other person, by whatever name called, who arranges or facilitates the supply of goods or services or both, or securities, between two or more persons", but expressly excludes "a person who supplies such goods or services or both or securities on his own account". The exclusion is integral to the definition, not a discretionary concession.

The agency distinction also finds statutory support in Section 2(5) of the CGST Act: an agent carries on the business of supply or receipt of goods or services "on behalf of another". Under Section 2(93)(a), where consideration is payable, the recipient is "the person who is liable to pay that consideration". These definitions assist in distinguishing the contractual recipient from persons incidentally benefiting from performance.

Five cumulative conditions for export

Section 2(6) of the IGST Act requires:

  1. The supplier to be located in India.
  2. The recipient to be located outside India.
  3. The place of supply to be outside India.
  4. Payment to have been received in convertible foreign exchange, or in Indian rupees wherever permitted by the Reserve Bank of India.
  5. The supplier and recipient not to be "merely establishments of a distinct person" under Explanation 1 to Section 8.

The fifth condition concerns establishments of the same person. Explanation 1 to Section 8 of the IGST Act includes a person having an establishment in India and another outside India. Explanation 2 recognises business conducted through a branch, agency or representational office as an establishment in that territory.

Circular No. 161/17/2021-GST clarifies that an Indian-incorporated company and a separately incorporated foreign company are separate persons. An Indian subsidiary's supply to its foreign parent is therefore not barred by Section 2(6)(v) merely because of group ownership; the remaining export conditions must still be fulfilled.

Place of supply and the relevant period

Section 13(2) of the IGST Act provides that, except for services specified in sub-sections (3) to (13), the place of supply "shall be the location of the recipient of services". Where that location is unavailable in the ordinary course of business, the proviso substitutes the supplier's location.

For the disputed periods, Section 13(8)(b) prescribed the supplier's location for intermediary services. The tribunal records that the Finance Act, 2026 omitted that clause. The omission must be distinguished from the continuing definition in Section 2(13); it does not retrospectively resolve classification for earlier periods. The dispute concerned supplies preceding the omission.

Section 13(3)(b) separately addresses services "supplied to an individual", whether the recipient or a person acting for the recipient, requiring that individual's physical presence with the supplier. Mere interaction with students in India does not, without establishing these statutory conditions, displace the general recipient-location rule.

Detailed Analysis

Actual performance must be distinguished from commercial facilitation

Circular No. 159/15/2021-GST identifies three foundational requirements: at least three parties, two distinct supplies, and the character of an agent, broker or similar person. The ancillary arranging or facilitating service must be "clearly identifiable and distinguished from the main supply". Counting every participant in the wider business chain is therefore insufficient.

Paragraph 3.5 states: "Sub-contracting for a service is not an intermediary service." Its explanation is substantive: the subcontractor supplies the main service, "either fully or a part thereof", rather than merely arranging its provision. The software-development illustration confirms that interaction with the principal contractor's customer does not change the character of an independently performed subcontract.

This distinction answers the department's argument that the taxpayer could not be a subcontractor because it did not itself provide education. The relevant enquiry was whether it performed the marketing and support obligations entrusted to it, not whether it delivered the ultimate educational programme. Otherwise, almost every outsourced business-support activity could be characterised as facilitating the recipient's downstream business.

Conversely, a bilateral agreement and invoicing to an overseas principal are not sufficient by themselves. The circular's machinery-sale illustration describes an intermediary invoicing only one principal. The decisive question remains whether the supplier performs the contracted service or arranges another supply between other persons.

The tribunal's application to the contractual arrangements

The tribunal treated the taxpayer's own-account performance, independent-contractor status and absence of agency powers as significant. The taxpayer used its own resources to perform substantive marketing and IT-enabled work. The separately contracted advisers' enrolment activities were not attributable to it merely because its work supported the same commercial objective.

Applying ejusdem generis, the tribunal read "any other person" in Section 2(13) in the context of the preceding expressions "broker" and "agent". It rejected an unrestricted interpretation encompassing an independent supplier simply because its services advanced another business's operations.

The cost-plus model reinforced this conclusion, particularly when contrasted with the advisers' success-linked commission. Nevertheless, payment terminology is evidentiary rather than determinative. The education-sector authorities discussed below demonstrate that commission-based remuneration does not invariably establish intermediary status.

GST authorities on subcontracted performance

In 2022 (11) TMI 743 - PUNJAB AND HARYANA HIGH COURT, the issue concerned BPO and IT services performed under a master subcontracting agreement. The taxpayer undertook deliverables, performance risks and service-level obligations for an overseas contractor, including direct delivery to that contractor's customers. The court held that actual performance was not arrangement or facilitation. The non-agency clause and absence of direct contracts with ultimate customers supported the conclusion, and the original refund order was restored. The decision establishes that customer-facing delivery under a subcontract is compatible with own-account supply.

That decision also applied consistency where the same agreement had previously been accepted and no material factual or legal change justified a different result. Its relevance is not that earlier acceptance overrides the statute, but that a changed classification requires a sustainable basis rather than a different description of unchanged contractual performance.

In 2025 (5) TMI 150 - KARNATAKA HIGH COURT, pre-sale and post-sale customer-support services supplied to foreign affiliates were examined against the same statutory and circular-based tests. The taxpayer performed the support service itself, was prohibited from acting as agent or entering sales contracts, and lacked contractual privity with end customers. The court rejected intermediary classification and quashed the refund rejection and recovery notice insofar as they rested on that finding. Other issues remained available for separate contest, illustrating that success on classification does not determine every refund objection.

Marketing and customer-support authorities under service tax

The doctrinal connection is express. Rule 2(f) of the Place of Provision of Services Rules, 2012 excluded a person providing "the main service or supplies the goods on his account". Circular No. 159/15/2021-GST recognises broad continuity between that definition and Section 2(13), apart from the addition of securities. Earlier decisions are therefore useful on classification, without transplanting their separate tax machinery into GST.

In 2023 (7) TMI 719 - DELHI HIGH COURT, marketing, administrative and support services were supplied under an independent-contractor agreement. The taxpayer could not represent or bind the overseas recipient, received cost-plus consideration unrelated to downstream sales and did not arrange a separate supply between other parties. The court upheld the conclusion that these were own-account services. This closely supports the distinction between performing marketing work and acting as a sales intermediary.

In 2023 (9) TMI 304 - DELHI HIGH COURT, the taxpayer supplied telecommunications infrastructure, customer care and billing support to an overseas recipient. It independently contracted with Indian operators on its own account. The court held that these arrangements represented substantive service provision rather than brokerage, and upheld export treatment and credit refund. The decision shows that procuring local inputs does not itself transform the supplier into an intermediary.

In 2024 (1) TMI 887 - CESTAT HYDERABAD, collections and contact-centre operations were performed under subcontracting and performance-level agreements. The taxpayer bore performance obligations to the overseas contractor, received cost-plus compensation and had no contractual privity with ultimate business partners. The tribunal held that the challenged activities formed part of the main service, not a separately identifiable facilitating supply. Its relevance lies in examining operational obligations rather than isolating customer-contact functions.

In 2025 (3) TMI 200 - CESTAT CHANDIGARH, promotional and marketing services were supplied as an independent contractor for cost-plus remuneration. The taxpayer invoiced the overseas recipient, had no customer contract and remained responsible for work it further subcontracted. The tribunal held that only the main promotional service was supplied, with no separate auxiliary facilitation service. Further outsourcing did not alter the taxpayer's responsibility or create intermediary status.

In 2024 (11) TMI 922 - CESTAT BANGALORE, research and development, marketing assistance, demonstrations and customer support were examined together. The agreements and invoices established principal-to-principal performance for the overseas recipient. The tribunal rejected the department's attempt to characterise those activities as mere facilitation and upheld export treatment. The decision reinforces that sales-related content does not dispense with proof of an intermediary arrangement.

In 2024 (10) TMI 147 - CESTAT NEW DELHI, brand-development and promotional obligations were performed on the taxpayer's own account. The tribunal found no contractual requirement to arrange another person's main service. Outsourcing some tasks did not change that conclusion, and the general recipient-location rule applied. The authority is relevant where a supplier remains responsible for an integrated service despite using subcontractors.

Education-sector comparisons

In 2024 (3) TMI 1178 - CESTAT NEW DELHI, recruitment, promotion, enrolment assistance and related liaison were performed for foreign universities. Although remuneration was described as commission, the taxpayer supplied the contracted services itself rather than arranging for a third party to perform them. The tribunal held that the services were exports and not intermediary services. The decision is particularly important against treating commission as a conclusive classification test.

In 2024 (8) TMI 399 - CESTAT CHANDIGARH, the taxpayer contracted only with an overseas education-services contractor, not with universities or students. For the period governed by the intermediary definition, the tribunal found subcontracted performance rather than a three-party facilitation arrangement. Export treatment was sustained. The contractual chain closely illustrates why the ultimate educational service and the independently performed subcontract must be identified separately.

The education-consultancy decision separately analysed by the GST tribunal concerned marketing and recruitment support supplied directly to foreign universities. The court held that incidental assistance to students did not establish intermediary status where the taxpayer did not charge students, bind universities or guarantee admission. The tribunal relied on that reasoning when accepting the taxpayer's export classification.

A further education-marketing authority discussed in that reasoning emphasised the contractual recipient, the person liable for consideration and the nature of the actual service. It rejected the proposition that advancing the foreign institution's business objective necessarily amounted to intermediary activity. This directly addresses attempts to substitute the location of an incidental beneficiary for the statutory enquiry.

The separately considered university-recruitment authority similarly held that recommending students did not make them the recipients of services paid for by foreign universities. Export relief remained subject to receipt of foreign-currency consideration. Its significance is the distinction between assisting an applicant operationally and supplying the contracted recruitment service to the university.

Other comparisons and contrary advance rulings

The sourcing-support authority analysed by the tribunal concerned supplier identification, factory visits, production monitoring and shipment support. Independent-contractor obligations, cost-plus remuneration, non-binding recommendations and the overseas recipient's freedom to select suppliers supported the conclusion that the taxpayer supplied business-support services on its own account. The comparison demonstrates that extensive coordination is not necessarily brokerage.

The tribunal also applied its earlier support-service reasoning that "any other person" must be understood in the context of broker-like or agent-like characteristics. Its relevance was to prevent an unrestricted reading of Section 2(13) that would override the express own-account exclusion.

The department relied on an advance ruling concerning vendor identification and quality monitoring, where the applicant was treated as facilitating supplies between its foreign holding company and Indian vendors. That conclusion turned on a facilitation character different from the subcontracted performance accepted here.

A separate advance ruling concerned promotion of foreign university courses for commission and classified the applicant as an intermediary. The contrasting education-sector decisions show why neither the industry description nor commission alone resolves the statutory enquiry.

The third advance ruling concerned support services to a foreign parent and also adopted intermediary classification. The tribunal declined to follow these advance rulings in preference to the High Court authorities. It did not establish a universal export rule for support services; it applied the judicial tests to the taxpayer's particular obligations.

Practical Implications

Classification requires a coherent contractual and evidentiary account. Relevant materials include the master agreement, service schedules, upstream contracts where necessary, adviser agreements, invoices, remittance evidence, transfer-pricing descriptions and records demonstrating actual deliverables. Expressions such as "liaison", "support" or "recruitment" require examination in their operational context.

  • Identify the precise service the taxpayer undertakes to perform and the person entitled to enforce that obligation.
  • Determine whether a separate supply between other principals is merely being arranged, rather than performed fully or partly by the taxpayer.
  • Examine authority to negotiate, represent or bind another person alongside responsibility for personnel, infrastructure and performance.
  • Reconcile invoicing, consideration and corporate identity. The tribunal rejected the identity objection where the relevant corporate change was not seriously disputed.
  • Test recipient location, payment realisation and separate legal personality independently of intermediary classification.

For refund consequences, Section 16(1)(a) of the IGST Act includes exports within "zero rated supply". For the disputed periods, Section 16(3)(a) permitted supply under bond or Letter of Undertaking without integrated tax and refund of unutilised credit, subject to prescribed requirements.

Section 54(3) of the CGST Act expressly recognises refund for "zero rated supplies made without payment of tax". Rule 89(2)(c) of the CGST Rules requires the export-service invoice statement and relevant Bank Realisation Certificates or Foreign Inward Remittance Certificates. Establishing export character therefore addresses the substantive classification objection, while applicable documentary and computation requirements remain relevant.

Key Takeaways

The governing distinction is between performing a service and arranging its performance by others. A subcontractor does not become an intermediary merely because it interacts with customers, supports recruitment or contributes to an overseas recipient's downstream business.

The tribunal's conclusion rests on the combined contractual and operational evidence: substantive own-account performance, independent responsibility, separate adviser arrangements and consideration received from the overseas recipient. Those features must be evaluated together, followed by a separate assessment of every export condition under Section 2(6). Export classification then provides the foundation-not a substitute-for compliance with the zero-rated refund framework.


Full Text:

2026 (10) TMI 1143 - GSTAT NEW DELHI-[PB]

Topics

Acts Income Tax