Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
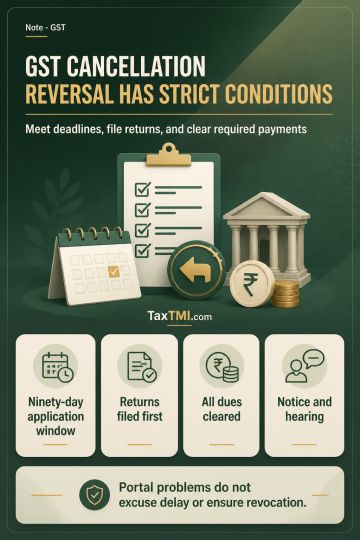
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
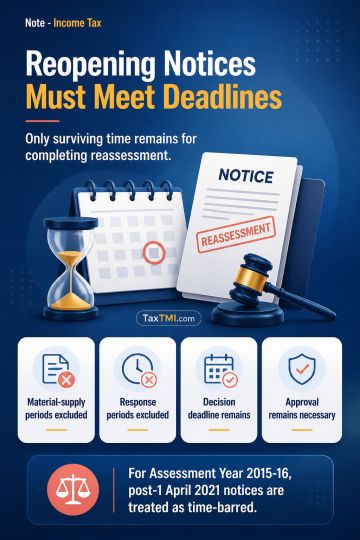
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
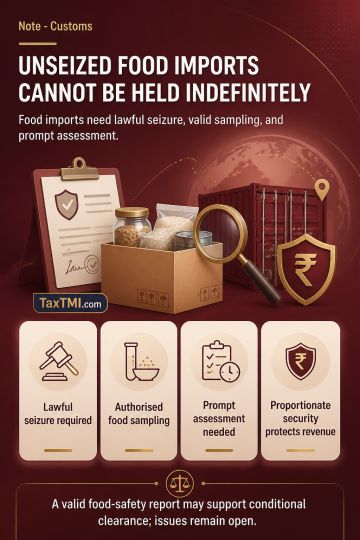
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
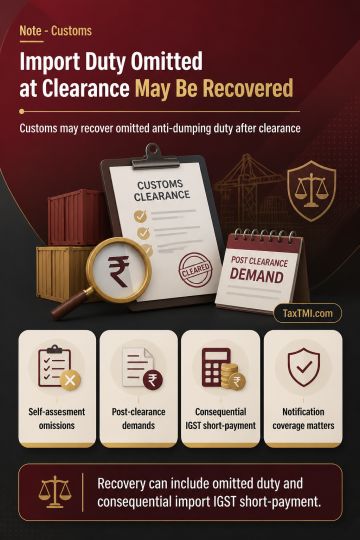
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Validity of Scrutiny Notice under Section 143(2) and Non-Conformity with CBDT-Prescribed Formats

23 September, 2026

Contents
Circulars
Acts
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

This is a neutral professional article. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.

2026 (7) TMI 1968 - ITAT BENGALURU (LB) (SB)

At a Glance

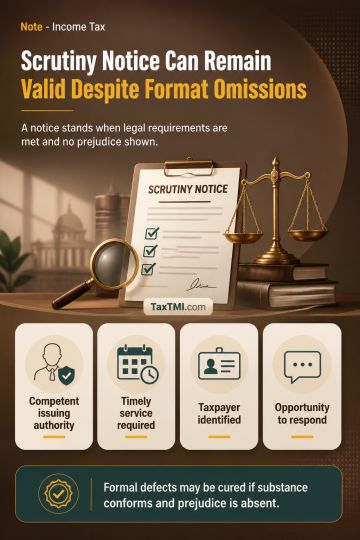
The validity of a scrutiny notice under Section 143 does not depend, by itself, upon conformity with the three formats prescribed in the CBDT Instruction dated 23 June 2017. The Special Bench has answered the reference against invalidation: a notice under section 143(2) that is otherwise issued and served within the statutory period, and which effectively conveys selection of the return for scrutiny, is not rendered invalid merely because it does not state whether the scrutiny is Limited Scrutiny, Complete Scrutiny or Compulsory Manual Scrutiny.

The decisive distinction is between a statutory condition for the assumption of jurisdiction and an administrative prescription governing the form and management of scrutiny proceedings. The 2017 Instruction is binding upon departmental authorities for administrative purposes, but its breach does not automatically create a jurisdictional defect where the Act itself does not require disclosure of the scrutiny category. Any defect of this kind is, in appropriate circumstances, protected by Section 292B, subject to the notice being in substance and effect consistent with the Act and the taxpayer not establishing actual prejudice.

The ruling does not dilute the separate rule that, where a case is in fact selected for limited scrutiny, the Assessing Officer must remain within the authorised scope unless the prescribed procedure for expansion is followed. The validity of the initiating notice and the legality of the eventual scope of enquiry remain analytically distinct questions.

Background & Context

The controversy arose from the CBDT Instruction on issue of notices under section 143(2) in revised format. It introduced three distinct templates: Limited Scrutiny under Computer Aided Scrutiny Selection, Complete Scrutiny under Computer Aided Scrutiny Selection, and Compulsory Manual Scrutiny. Paragraph 3 directs that all scrutiny notices under section 143(2) "shall henceforth, be issued in these revised formats only".

The limited-scrutiny template states that the return has been selected for scrutiny and that specified issues have been identified for examination. The complete-scrutiny template states that the return has been selected for Complete Scrutiny. The compulsory-manual-scrutiny template refers to selection on the basis of the applicable manual compulsory guideline. Each format also contemplates an opportunity to provide evidence or information and provides for electronic assessment proceedings.

These formats were intended to standardise departmental communication in an electronic assessment environment. A divergence subsequently emerged in Tribunal decisions: one approach treated non-use of the prescribed format as fatal to the notice and consequential assessment; the other treated it as a curable irregularity where the taxpayer was informed of scrutiny, participated effectively, and could not demonstrate prejudice. The Special Bench resolved this divergence in 2026 (7) TMI 1968 - ITAT BENGALURU (LB) (SB).

Key Issues / Provisions

Statutory content of a scrutiny notice

Section 143(2) applies where a return has been furnished under section 139 or in response to a notice under section 142(1). It authorises the Assessing Officer or prescribed authority, where it considers it necessary or expedient to ensure that income is not understated, loss is not excessively computed, or tax is not underpaid, to serve a notice requiring the assessee, on a specified date, "either to attend the office of the Assessing Officer or to produce, or cause to be produced before the Assessing Officer any evidence" relied upon in support of the return.

The proviso is equally material: "no notice under this sub-section shall be served on the assessee after the expiry of three months from the end of the financial year in which the return is furnished." Thus, issuance and service within the statutory time limit, coupled with the statutory requirement to attend or produce evidence in support of the return, form the central requirements under section 143(2).

Board instructions and their administrative force

Section 119(1) permits the Board to issue orders, instructions and directions for the proper administration of the Act, and requires income-tax authorities and persons employed in executing the Act to "observe and follow" them. Section 119(2)(a) further enables directions, not prejudicial to assessees, concerning guidelines, principles or procedures in assessment and collection work.

The 2017 Instruction is therefore binding upon departmental authorities as an administrative direction. The question, however, is not merely whether it binds officers; it is whether its breach converts an otherwise statutorily compliant section 143(2) notice into an invalid assumption of jurisdiction.

Curative and service-related provisions

Section 292B provides that no notice, assessment or other proceeding is invalid merely because of a mistake, defect or omission if it is "in substance and effect in conformity with or according to the intent and purpose of this Act." Circular No. 179/1975 explains that this provision addresses purely technical objections without substance that might otherwise impede assessment proceedings.

Section 292BB operates in a different field. Where an assessee appears or co-operates in an assessment or reassessment inquiry, it deems a notice to have been duly served in time and in accordance with the Act, and precludes objections that it was not served, was not timely served, or was served improperly. This deeming rule is subject to the proviso where the objection is raised before completion of assessment. It concerns service-related objections; Section 292B addresses defects in a notice or proceeding that otherwise meets the substantive statutory test.

Section 282A separately requires a notice to be signed and issued in paper form or communicated electronically as prescribed, and deems authentication where the name and office of a designated income-tax authority is printed, stamped or otherwise written on it.

Detailed Analysis

The Special Bench ruling: form does not displace statutory substance

In 2026 (7) TMI 1968 - ITAT BENGALURU (LB) (SB), the notice had been issued within limitation, duly served, and followed by inquiries under section 142(1). The taxpayer had participated in the proceedings without objecting to the notice format before the Assessing Officer. The challenge was confined to the absence of conformity with the 2017 prescribed format.

The Special Bench held that neither the Act nor the Rules prescribe a statutory format for a section 143(2) notice. Crucially, the expressions "Limited Scrutiny", "Complete Scrutiny" and "Manual Scrutiny" do not occur in section 143(2). They are administrative classifications used for management of scrutiny cases. Accordingly, their omission from the notice does not, by itself, negate the statutory substance of a notice that informs the taxpayer of scrutiny and calls for participation and supporting evidence.

The Bench applied the principle that where the legislature has expressly stipulated particular conditions, further jurisdictional conditions cannot be imported through an administrative instruction. A Board instruction may regulate departmental conduct and may expose non-compliant officers to administrative consequences; nevertheless, invalidation of a proceeding follows only where the breach affects a statutory condition precedent or results in demonstrable prejudice. The referred question was consequently answered in the negative and in favour of the revenue.

The ruling adopts a fact-sensitive test. Participation alone is not treated as a universal cure for every jurisdictional defect. Rather, the relevant enquiry is whether the statutory notice existed, was issued by a competent authority within limitation, identified the taxpayer and assessment year, conveyed scrutiny, afforded the statutory opportunity, and whether any real confusion or prejudice arose from the alleged formal deviation.

Earlier contrary Tribunal decisions on notice format

2024 (11) TMI 970 - ITAT KOLKATA admitted an additional legal ground concerning the section 143(2) notice and treated the prescribed format as significant. Its operative conclusion, however, rested on a finding that additions had been made beyond the limited-scrutiny issue without compliance with conversion safeguards. Its continuing relevance is therefore strongest on unauthorised expansion of limited scrutiny rather than on format non-conformity alone.

2024 (11) TMI 1455 - ITAT KOLKATA treated a notice not falling within any prescribed 2017 format as invalid and quashed the consequential assessment. It proceeded on the view that CBDT instructions are mandatory and binding. That conclusion on the standalone format issue is contrary to the Special Bench's determination that administrative format requirements cannot be elevated into an unstated statutory jurisdictional condition.

2025 (3) TMI 1494 - ITAT KOLKATA similarly held that a notice describing only computer-aided scrutiny selection, without identifying the scrutiny category, was invalid and that the consequential assessment could not survive. The Special Bench specifically considered this line of authority and found that it had not addressed the curative scope of section 292B in the context of a notice that otherwise fulfilled section 143(2).

2025 (4) TMI 1668 - ITAT KOLKATA set aside a notice not in the prescribed format and treated the consequential assessment as void. It also noted the characterisation of the 2017 communication as an internal departmental communication. The Special Bench clarifies the legal consequence of that character: even an instruction binding on officers does not, without more, invalidate statutory proceedings that remain substantively compliant.

2025 (5) TMI 786 - ITAT KOLKATA held that omission to specify limited, complete or compulsory manual scrutiny violated the Board's instruction and invalidated the assessment. This is another contrary format-based conclusion that cannot govern the referred issue after the Special Bench's negative answer.

2025 (7) TMI 1907 - ITAT DELHI likewise treated use of a non-prescribed format as fatal because the format was understood to define the nature and scope of scrutiny. The Special Bench rejected that reasoning to the extent it equates the Board-prescribed format with a statutory condition for assumption of jurisdiction.

Scope of limited scrutiny remains a separate jurisdictional restraint

Instruction on unauthorised expansion of limited scrutiny states that, in limited-scrutiny cases, the Assessing Officer cannot travel beyond the selected issues. It reiterates the purpose of preventing fishing and roving inquiries and records that expansion without recorded reasons and the stipulated approval was viewed seriously.

2023 (10) TMI 921 - CALCUTTA HIGH COURT upheld the conclusion that additions outside the limited-scrutiny mandate were beyond jurisdiction where the conversion safeguards had not been followed. The decision concerns the actual scope of assessment, not a defect in the notice template. It therefore remains consistent with the Special Bench distinction.

2023 (8) TMI 888 - CALCUTTA HIGH COURT similarly affirmed that inquiries beyond the specified limited-scrutiny issues could not begin before the requisite written approval for conversion to complete scrutiny. It reinforces that the statutory assessment process and binding procedural safeguards restrict substantive enlargement of an inquiry, even though mere omission of the scrutiny label in the initial notice is not itself fatal.

Practical Implications

  • A challenge based solely on non-mention of Limited Scrutiny, Complete Scrutiny or Compulsory Manual Scrutiny in a section 143(2) notice is insufficient where the statutory requirements are otherwise fulfilled and no actual prejudice is established.

  • Notice review should begin with statutory essentials: eligibility of the return for section 143(2), service within the three-month limitation, competence and authentication of the issuing authority, identification of the taxpayer and assessment year, and a requirement to attend or furnish evidence in support of the return.

  • Where a taxpayer asserts confusion or prejudice, the assessment record, subsequent notices, questionnaires, replies and order-sheet material become significant. The issue is necessarily fact-dependent.

  • A format objection must not be confused with a challenge based on absence of notice, delayed service, notice to an incorrect or non-existent person, lack of authority, or substantive excess beyond the permissible scope of limited scrutiny. Those defects raise different legal questions.

  • For limited-scrutiny matters, practitioners should preserve and examine the original selection reason, the issues specified for verification, correspondence initiating additional inquiries, recorded reasons, and approval material for conversion to complete scrutiny. The later section 142(1) notice may communicate specific information requirements, but it cannot legitimise an unauthorised expansion of a limited-scrutiny inquiry.

  • Departmental authorities remain bound by the 2017 format instruction under section 119. The ruling concerns the validity of the assessment proceeding; it does not treat non-observance of the instruction as immaterial for administrative accountability.

Key Takeaways

  • A section 143(2) notice is not invalid merely because it departs from the CBDT's 2017 revised format.

  • The statutory touchstone is substantive conformity with section 143(2), including timely service and a meaningful opportunity to support the return.

  • Section 292B protects defects of form where the notice remains in substance and effect consistent with the Act; Section 292BB addresses objections concerning service, timeliness of service and improper service.

  • CBDT instructions under section 119 bind departmental authorities, but not every administrative departure results in nullity of an otherwise valid statutory proceeding.

  • The restriction on expanding limited scrutiny without prescribed safeguards remains enforceable and must be assessed independently of the format of the initiating notice.


Full Text:

2026 (7) TMI 1968 - ITAT BENGALURU (LB) (SB)

Topics

Acts Income Tax